
Lennar (LEN)
Market Price (10/5/2026): $80.5 | Market Cap: $19.7 BilInvestor Relations Sector: Consumer Discretionary | Industry: Homebuilding
Lennar (LEN)
Market Price (10/5/2026): $80.5Market Cap: $19.7 BilSector: Consumer DiscretionaryIndustry: Homebuilding
Investment Highlights Why It Matters Detailed financial logic regarding cash flow yields vs trend-riding momentum.
Attractive yieldTotal YieldTotal Yield = Earnings Yield + Dividend Yield, Earnings Yield = Net Income / Market Cap Dividend Yield = Total Dividends / Market Cap is 12%, Dividend Yield is 2.6%, ERPEquity Risk Premium (ERP) = Total Yield - Risk Free Rate, Reflects the premium above risk free assets offered by the investment. is 8.0% Stock buyback supportStock Buyback 3Y Total is 5.3 Bil Low stock price volatilityVol 12M is 37% Megatrend and thematic driversMegatrends include Smart Buildings & Proptech, and Sustainable & Green Buildings. Themes include IoT for Buildings, Energy Efficient Building Materials, Show more. | Weak multi-year price returns2Y Excs Rtn is -90%, 3Y Excs Rtn is -106% | Expensive valuation multiplesP/CFOPrice/(Cash Flow from Operations). CFO is cash before capital expenditures. is 270x Weak revenue growthRev Chg LTMRevenue Change % Last Twelve Months (LTM) is -7.2%, Rev Chg 3Y AvgRevenue Change % averaged over trailing 3 years is -0.7%, Rev Chg QQuarterly Revenue Change % is -13% Key risksLEN key risks include [1] significant margin compression and eroding profitability driven by the need to offer increased sales incentives and price reductions. |
| Attractive yieldTotal YieldTotal Yield = Earnings Yield + Dividend Yield, Earnings Yield = Net Income / Market Cap Dividend Yield = Total Dividends / Market Cap is 12%, Dividend Yield is 2.6%, ERPEquity Risk Premium (ERP) = Total Yield - Risk Free Rate, Reflects the premium above risk free assets offered by the investment. is 8.0% |
| Stock buyback supportStock Buyback 3Y Total is 5.3 Bil |
| Low stock price volatilityVol 12M is 37% |
| Megatrend and thematic driversMegatrends include Smart Buildings & Proptech, and Sustainable & Green Buildings. Themes include IoT for Buildings, Energy Efficient Building Materials, Show more. |
| Weak multi-year price returns2Y Excs Rtn is -90%, 3Y Excs Rtn is -106% |
| Expensive valuation multiplesP/CFOPrice/(Cash Flow from Operations). CFO is cash before capital expenditures. is 270x |
| Weak revenue growthRev Chg LTMRevenue Change % Last Twelve Months (LTM) is -7.2%, Rev Chg 3Y AvgRevenue Change % averaged over trailing 3 years is -0.7%, Rev Chg QQuarterly Revenue Change % is -13% |
| Key risksLEN key risks include [1] significant margin compression and eroding profitability driven by the need to offer increased sales incentives and price reductions. |
Qualitative Assessment
AI Analysis | Feedback
Lennar (LEN) stock has lost about 10% since 6/30/2026 because of the following key factors:
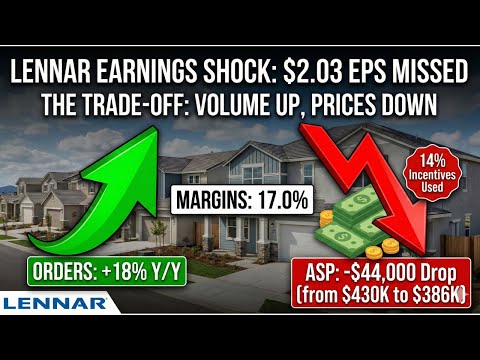
1. Disappointing Fiscal Q3 2026 Results and Reduced Outlook. Lennar reported adjusted diluted earnings per share of $1.23 for its fiscal third quarter ended August 31, 2026, missing the analyst consensus of $1.29. Quarterly revenue also fell short, coming in at $8.05 billion against an expected $8.23 billion. Following these results, the company lowered its full-year 2026 delivery guidance to a range of 80,000–81,000 homes, down from the previously anticipated 82,000–83,000 homes.
2. Significant Gross Margin Compression and Increased Sales Incentives. Homebuilding gross margins declined to 15.8% in fiscal Q3 2026, a notable decrease from 17.5% in the prior year period. This contraction was primarily attributed to lower revenue per square foot and higher land costs. To maintain sales volume in a challenging market, Lennar utilized approximately 12% in sales incentives and base-price adjustments, which contributed to a 3% decrease in the average delivered home price to $372,000.
Show more
Lennar (LEN) stock has lost about 10% since 6/30/2026 because of the following key factors:
1. Disappointing Fiscal Q3 2026 Results and Reduced Outlook. Lennar reported adjusted diluted earnings per share of $1.23 for its fiscal third quarter ended August 31, 2026, missing the analyst consensus of $1.29. Quarterly revenue also fell short, coming in at $8.05 billion against an expected $8.23 billion. Following these results, the company lowered its full-year 2026 delivery guidance to a range of 80,000–81,000 homes, down from the previously anticipated 82,000–83,000 homes.
2. Significant Gross Margin Compression and Increased Sales Incentives. Homebuilding gross margins declined to 15.8% in fiscal Q3 2026, a notable decrease from 17.5% in the prior year period. This contraction was primarily attributed to lower revenue per square foot and higher land costs. To maintain sales volume in a challenging market, Lennar utilized approximately 12% in sales incentives and base-price adjustments, which contributed to a 3% decrease in the average delivered home price to $372,000.
3. Elevated Mortgage Rates and Worsening Housing Affordability. A significant macroeconomic headwind was the continued surge in mortgage rates during the period. The average 30-year fixed mortgage rate rose from approximately 6.6% in June to around 7% by late September 2026, with some reports indicating rates as high as 7.30% to 7.38% by the end of September. This increase severely impacted housing affordability and consumer confidence, leading to a 9% year-over-year decrease in new home orders for Lennar in fiscal Q3 2026.
4. Negative Analyst Sentiment and Price Target Revisions. The company's missed earnings and lowered guidance led to a deterioration in analyst sentiment. Several firms either reiterated bearish ratings or cut their price targets for Lennar. For example, Citigroup cut its price target from $104 to $88 on July 15, 2026, and further to $85 on September 21, 2026. Additionally, Morgan Stanley initiated coverage with an "Underweight" rating and a $65 price target on October 1, 2026, citing margin concerns.
Show less
Stock Movement Drivers
Fundamental Drivers
The -11.3% change in LEN stock from 6/30/2026 to 10/4/2026 was primarily driven by a -11.3% change in the company's P/E Multiple.| (LTM values as of) | 6302026 | 10042026 | Change |
|---|---|---|---|
| Stock Price ($) | 89.95 | 79.81 | -11.3% |
| Change Contribution By: | |||
| Total Revenues ($ Mil) | 33,175 | 33,175 | 0.0% |
| Net Income Margin (%) | 5.4% | 5.4% | 0.0% |
| P/E Multiple | 12.3 | 10.9 | -11.3% |
| Shares Outstanding (Mil) | 244 | 244 | 0.0% |
| Cumulative Contribution | -11.3% |
Market Drivers
6/30/2026 to 10/4/2026| Return | Correlation | |
|---|---|---|
| LEN | -11.3% | |
| Market (SPY) | 3.1% | 41.1% |
| Sector (XLY) | -6.2% | 42.0% |
Fundamental Drivers
The -7.1% change in LEN stock from 3/31/2026 to 10/4/2026 was primarily driven by a -11.3% change in the company's Net Income Margin (%).| (LTM values as of) | 3312026 | 10042026 | Change |
|---|---|---|---|
| Stock Price ($) | 85.87 | 79.81 | -7.1% |
| Change Contribution By: | |||
| Total Revenues ($ Mil) | 34,187 | 33,175 | -3.0% |
| Net Income Margin (%) | 6.1% | 5.4% | -11.3% |
| P/E Multiple | 10.4 | 10.9 | 4.6% |
| Shares Outstanding (Mil) | 252 | 244 | 3.2% |
| Cumulative Contribution | -7.1% |
Market Drivers
3/31/2026 to 10/4/2026| Return | Correlation | |
|---|---|---|
| LEN | -7.1% | |
| Market (SPY) | 18.6% | 42.2% |
| Sector (XLY) | 1.2% | 48.1% |
Fundamental Drivers
The -35.4% change in LEN stock from 9/30/2025 to 10/4/2026 was primarily driven by a -41.4% change in the company's Net Income Margin (%).| (LTM values as of) | 9302025 | 10042026 | Change |
|---|---|---|---|
| Stock Price ($) | 123.55 | 79.81 | -35.4% |
| Change Contribution By: | |||
| Total Revenues ($ Mil) | 35,372 | 33,175 | -6.2% |
| Net Income Margin (%) | 9.2% | 5.4% | -41.4% |
| P/E Multiple | 9.9 | 10.9 | 10.5% |
| Shares Outstanding (Mil) | 260 | 244 | 6.5% |
| Cumulative Contribution | -35.4% |
Market Drivers
9/30/2025 to 10/4/2026| Return | Correlation | |
|---|---|---|
| LEN | -35.4% | |
| Market (SPY) | 16.5% | 33.6% |
| Sector (XLY) | -7.6% | 43.0% |
Fundamental Drivers
The -25.3% change in LEN stock from 9/30/2023 to 10/4/2026 was primarily driven by a -53.8% change in the company's Net Income Margin (%).| (LTM values as of) | 9302023 | 10042026 | Change |
|---|---|---|---|
| Stock Price ($) | 106.89 | 79.81 | -25.3% |
| Change Contribution By: | |||
| Total Revenues ($ Mil) | 33,440 | 33,175 | -0.8% |
| Net Income Margin (%) | 11.7% | 5.4% | -53.8% |
| P/E Multiple | 7.8 | 10.9 | 40.7% |
| Shares Outstanding (Mil) | 283 | 244 | 15.7% |
| Cumulative Contribution | -25.3% |
Market Drivers
9/30/2023 to 10/4/2026| Return | Correlation | |
|---|---|---|
| LEN | -25.3% | |
| Market (SPY) | 86.2% | 36.4% |
| Sector (XLY) | 39.8% | 44.5% |
Price Returns Compared
| 2021 | 2022 | 2023 | 2024 | 2025 | 2026 | Total [1] | |
|---|---|---|---|---|---|---|---|
| Returns | |||||||
| LEN Return | 54% | -21% | 67% | -7% | -23% | -19% | 17% |
| Peers Return | 51% | -22% | 90% | 6% | -0% | -4% | 124% |
| S&P 500 Return | 27% | -19% | 24% | 23% | 16% | 12% | 104% |
Monthly Win Rates [3] | |||||||
| LEN Win Rate | 75% | 42% | 58% | 67% | 33% | 56% | |
| Peers Win Rate | 75% | 42% | 65% | 57% | 45% | 44% | |
| S&P 500 Win Rate | 75% | 42% | 67% | 75% | 67% | 44% | |
Max Drawdowns [4] | |||||||
| LEN Max Drawdown | -16% | -44% | -22% | -29% | -28% | -37% | |
| Peers Max Drawdown | -21% | -42% | -21% | -26% | -25% | -25% | |
| S&P 500 Max Drawdown | -5% | -25% | -10% | -8% | -19% | -9% | |
[1] Cumulative total returns since the beginning of 2021
[2] Peers: DHI, PHM, NVR, TOL, MTH. See LEN Returns vs. Peers.
[3] Win Rate = % of calendar months in which monthly returns were positive
[4] Max drawdown represents maximum peak-to-trough decline within a year
[5] 2026 data is for the year up to 10/2/2026 (YTD)
How Low Can It Go
| Event | LEN | S&P 500 |
|---|---|---|
| 2025 US Tariff Shock | ||
| % Loss | -15.0% | -18.8% |
| % Gain to Breakeven | 17.7% | 23.1% |
| Time to Breakeven | 111 days | 79 days |
| Summer-Fall 2023 Five Percent Yield Shock | ||
| % Loss | -18.9% | -9.5% |
| % Gain to Breakeven | 23.3% | 10.5% |
| Time to Breakeven | 20 days | 24 days |
| 2022 Inflation Shock & Fed Tightening | ||
| % Loss | -41.8% | -24.5% |
| % Gain to Breakeven | 71.9% | 32.4% |
| Time to Breakeven | 308 days | 427 days |
| 2020 COVID-19 Crash | ||
| % Loss | -58.3% | -33.7% |
| % Gain to Breakeven | 140.0% | 50.9% |
| Time to Breakeven | 121 days | 140 days |
| Q4 2018 Fed Policy Error / Growth Scare | ||
| % Loss | -17.6% | -19.2% |
| % Gain to Breakeven | 21.4% | 23.8% |
| Time to Breakeven | 16 days | 105 days |
| 2015-2016 China Devaluation / Global Growth Scare | ||
| % Loss | -29.8% | -12.2% |
| % Gain to Breakeven | 42.4% | 13.9% |
| Time to Breakeven | 488 days | 62 days |
In The Past
Lennar's stock fell -15.0% during the 2025 US Tariff Shock. Such a loss loss requires a 17.7% gain to breakeven.
Preserve Wealth
Limiting losses and compounding gains is essential to preserving wealth.
Asset Allocation
Actively managed asset allocation strategies protect wealth. Learn more.
| Event | LEN | S&P 500 |
|---|---|---|
| 2022 Inflation Shock & Fed Tightening | ||
| % Loss | -41.8% | -24.5% |
| % Gain to Breakeven | 71.9% | 32.4% |
| Time to Breakeven | 308 days | 427 days |
| 2020 COVID-19 Crash | ||
| % Loss | -58.3% | -33.7% |
| % Gain to Breakeven | 140.0% | 50.9% |
| Time to Breakeven | 121 days | 140 days |
| 2015-2016 China Devaluation / Global Growth Scare | ||
| % Loss | -29.8% | -12.2% |
| % Gain to Breakeven | 42.4% | 13.9% |
| Time to Breakeven | 488 days | 62 days |
| 2013 Taper Tantrum | ||
| % Loss | -21.8% | -0.2% |
| % Gain to Breakeven | 27.9% | 0.2% |
| Time to Breakeven | 154 days | 1 days |
| 2011 US Debt Ceiling Crisis & European Contagion | ||
| % Loss | -31.7% | -17.9% |
| % Gain to Breakeven | 46.3% | 21.8% |
| Time to Breakeven | 105 days | 123 days |
| 2010 Eurozone Sovereign Debt Crisis / Flash Crash | ||
| % Loss | -32.3% | -15.4% |
| % Gain to Breakeven | 47.6% | 18.2% |
| Time to Breakeven | 189 days | 125 days |
| 2008-2009 Global Financial Crisis | ||
| % Loss | -79.2% | -53.4% |
| % Gain to Breakeven | 379.9% | 114.4% |
| Time to Breakeven | 299 days | 1085 days |
| Summer 2007 Credit Crunch | ||
| % Loss | -28.3% | -8.6% |
| % Gain to Breakeven | 39.5% | 9.5% |
| Time to Breakeven | 1800 days | 47 days |
In The Past
Lennar's stock fell -15.0% during the 2025 US Tariff Shock. Such a loss loss requires a 17.7% gain to breakeven.
Preserve Wealth
Limiting losses and compounding gains is essential to preserving wealth.
Asset Allocation
Actively managed asset allocation strategies protect wealth. Learn more.
About Lennar (LEN)
Lennar Corporation (LEN) is a leading homebuilder operating primarily under the Lennar brand across the United States. Its core business focuses on the construction and sale of various single-family homes, including both attached and detached properties. The company is also actively involved in the purchase, development, and sale of residential land, which forms the foundation for its housing projects.
Beyond its primary homebuilding activities, Lennar offers an integrated suite of financial services to support homebuyers, including residential mortgage financing, title insurance, and closing services. The company further diversifies its operations through a multifamily segment, which involves the development, construction, and management of rental properties, and engages in fund investment activities. It also originates and sells securitization commercial mortgage loans.
Lennar serves a broad spectrum of the U.S. housing market, catering to diverse customer needs. Its primary customers include first-time homebuyers, individuals looking to move up to a larger home, active adult communities, and the luxury home segment. The company operates through distinct geographic segments across the East, Central, Texas, and West regions of the United States, highlighting its widespread national presence.
AI Analysis | Feedback
The General Motors of new home construction.
AI Analysis | Feedback
- Homebuilding: Construction and sale of single-family attached and detached homes.
- Residential Land Development and Sales: Purchase, development, and sale of residential land.
- Multifamily Rental Property Development and Management: Development, construction, and management of multifamily rental properties.
- Residential Mortgage Financing: Providing residential mortgage loans for home buyers.
- Title Insurance and Closing Services: Offering title insurance and closing services for real estate transactions.
- Commercial Mortgage Loan Origination and Securitization: Originating and selling securitized commercial mortgage loans.
- Fund Investment Activity: Engaging in various fund investment activities.
AI Analysis | Feedback
Lennar Corporation (LEN) primarily sells its homes and services to individual homebuyers.
The categories of customers it serves include:
- First-time homebuyers
- Move-up homebuyers
- Active adult homebuyers
AI Analysis | Feedback
AI Analysis | Feedback
Stuart Miller is the son of co-founder Leonard Miller, who took Lennar public in 1971. He began working at Lennar Corporation in the 1980s. Miller became the Chief Executive Officer of Lennar in 1997. He assumed the role of Executive Chairman in April 2018. From 1997 until 2005, he served as Chairman of the Board of LNR Property Corporation, a commercial real estate entity that was spun off from Lennar and later sold in February 2005.
Diane Bessette, Chief Financial Officer
Diane Bessette joined Lennar Corporation in 1995. During her tenure, she held various senior leadership positions, including Corporate Controller from 1997 to 2008. She was named Vice President in 2000 and served as Treasurer from February 2008 until April 2024. Bessette was appointed Chief Financial Officer in April 2018.
Katherine Lee Martin, Chief Legal Officer and Secretary
Katherine Lee Martin serves as Lennar's Chief Legal Officer and Secretary. She is part of a leadership team composed of innovative leaders and industry experts.
Fred Rothman, Chief Operating Officer
Fred Rothman is the Chief Operating Officer of Lennar Corporation. He has also held roles such as President of Eastern Homebuilding Operations and Regional President at Lennar.
Bruce Gross, Chief Executive Officer, Lennar Financial Services
Bruce Gross is the Chief Executive Officer of Lennar Financial Services, which provides mortgage financing, title insurance, and homeowners insurance. He previously served as Vice President and Chief Financial Officer of Lennar. Since joining Lennar in 1997, Gross has been instrumental in the company's strategic and operating initiatives, including multiple acquisitions, contributing significantly to Lennar's growth. Before joining Lennar, he helped launch Pacific Greystone Corporation and supported its growth through an initial public offering and its subsequent acquisition by Lennar.
AI Analysis | Feedback
The key risks to Lennar's business are primarily driven by macroeconomic factors impacting the housing market and internal operational pressures.
- Interest Rate Sensitivity and Housing Affordability: High mortgage rates significantly dampen new-home demand and overall affordability, directly impacting Lennar's home sales and its financial services segment. A sustained period of elevated rates could further curtail sales volumes and reduce profitability, as evidenced by Lennar's recent performance lagging the S&P 500 due to higher mortgage rates squeezing demand. Higher interest rates also increase Lennar's costs for financing construction projects and land acquisition.
- Cyclical Downturns and Economic Uncertainty: The homebuilding industry is inherently cyclical and highly sensitive to broader economic conditions, employment levels, and consumer sentiment. A significant economic slowdown, a spike in unemployment, or geopolitical uncertainty could lead to reduced consumer confidence, increased home sale cancellations, and decreased demand for new homes.
- Margin Pressure from Costs and Incentives: Lennar faces ongoing pressure on its gross margins due to various factors. These include the use of buyer incentives and mortgage-rate buy-downs to stimulate sales in a challenging market, which can erode profitability. Additionally, rising material costs, labor shortages, and increasing land costs can inflate construction expenses and delay deliveries, further compressing margins.
AI Analysis | Feedback
The emergence of advanced construction technologies, such as large-scale 3D printing for homes and highly automated modular building systems, presents a clear emerging threat to traditional homebuilders like Lennar. These technologies promise to significantly reduce construction time, labor costs, and material waste, potentially enabling faster, more affordable, and more sustainable housing production. If these methods achieve widespread adoption and scalability, they could disrupt established construction practices and create a competitive disadvantage for companies relying primarily on conventional stick-built construction methods.
AI Analysis | Feedback
Lennar Corporation operates as a homebuilder and provides financial services, primarily in the United States. Its main addressable markets in the U.S. include residential construction, mortgage financing, and title insurance.
- Residential Construction Market (U.S.): The U.S. residential construction market size is estimated at USD 1.41 trillion in 2026, with projections to reach USD 1.76 trillion by 2031, growing at a compound annual growth rate (CAGR) of 4.53% between 2026 and 2031. For context, residential construction represented 54.3% of the total U.S. construction market in 2025, which was valued at USD 2.2 trillion.
- Mortgage Financing Market (U.S.): The total single-family mortgage origination volume in the U.S. is expected to reach $2.2 trillion in 2026, up from an estimated $2.0 trillion in 2025.
- Title Insurance Market (U.S.): The market size of the Title Insurance in the U.S. is estimated at $17.1 billion in 2025. The industry generated $4.5 billion in title insurance premiums during the second quarter of 2025.
AI Analysis | Feedback
Lennar (LEN) is expected to drive future revenue growth over the next 2-3 years through several key strategies aimed at navigating the current housing market and leveraging operational strengths:
- Increased Home Deliveries and Volume Focus: Lennar has communicated a clear objective to increase its volume of home deliveries. For instance, the company is targeting approximately 85,000 home deliveries in 2026. This focus on consistent and high-volume production is a direct driver of revenue growth, as more units sold translate to higher top-line figures.
- Enhanced Operational Efficiency and Cost Management: The company is prioritizing operational improvements, including reducing direct construction costs and improving cycle times for home construction. These efficiencies, such as an 11% year-over-year reduction in cycle time for single-family detached homes to an all-time low of 122 days in Q1 2026, allow Lennar to maintain competitiveness and offer homes at more attractive price points, thereby stimulating demand and supporting revenue growth.
- Leveraging an Asset-Light Land Strategy: Lennar continues to expand its "asset-light" approach to land acquisition through off-balance sheet land banking relationships. This strategy reduces capital intensity and risk, improves inventory turnover (from 1.5% to 1.7% year-over-year in Q1 2025 and 2.2x to 2.5x quarter-over-quarter in Q1 2026), and enables the company to adapt more quickly to market conditions, supporting sustained homebuilding volume and revenue.
- Technology-Driven Sales and Customer Engagement: Investments in technology are improving customer engagement quality scores (up 7%) and increasing the efficiency of the sales process, including an 11% quarter-over-quarter increase in kept sales appointments. This digital transformation aims to convert online interest into actual home sales more effectively, directly contributing to revenue generation.
- Focus on Affordability and Meeting Market Demand: Recognizing challenges like elevated interest rates and affordability pressures, Lennar is adapting its offerings to meet market demand by focusing on delivering homes at prices and with incentives that buyers can afford. This includes refining products and optimizing "Everything's Included" packages, which helps maintain sales pace and volume in a challenging environment.
AI Analysis | Feedback
Share Repurchases
- In January 2024, Lennar's Board of Directors authorized an expansion of its stock repurchase program, allowing for up to $5 billion in buybacks of Class A or Class B common stock with no set expiration date.
- Lennar repurchased $2.256 billion in shares during fiscal year 2024.
- In fiscal year 2025, the company repurchased $1.7 billion of its common stock.
Inbound Investments
- In March 2021, Lennar announced the formation of the Upward America Venture, which was initially capitalized with a total equity commitment of $1.25 billion. This venture, led by Centerbridge alongside Allianz Real Estate and other institutional investors, focuses on acquiring single-family homes for rent.
Outbound Investments
- In November 2024, Lennar entered into a definitive agreement to acquire Rausch Coleman Homes' homebuilding operations for $1 billion, expanding its market presence and contributing to its 2025 growth targets; the acquisition was completed in February 2025.
- Lennar made strategic technology investments in unconsolidated entities, totaling $239.3 million in fiscal 2024 and $127.5 million in fiscal 2023.
- In February 2025, Lennar completed the spin-off of Millrose Properties, Inc., an entity focused on land acquisition, development, and management, which is expected to have an asset base of $6.0-$8.0 billion.
Capital Expenditures
- From fiscal year 2021 to 2025, Lennar's capital expenditures averaged $116.5 million annually.
- Capital expenditures for Lennar peaked in fiscal year 2025 at $188.6 million.
- The primary focus of these capital expenditures is on Lennar's homebuilding operations, including the construction and sale of single-family homes and the development of residential land.
Peer Outperformance in Homebuilding
| Ticker | Name | Rev Growth 3Y Avg | P/E | 1Y | 3Y | 5Y | 5Y Gap |
|---|---|---|---|---|---|---|---|
| LEN | Lennar | -0.7% | 10.9x | -37.4% | -22.9% | -5.9% | — |
| PHM | PulteGroup | -0.5% | 11.5x | -15.2% | 64.8% | 160.7% | +167pp |
| TOL | Toll Brothers | 0.2% | 10.7x | -3.6% | 97.2% | 159.5% | +165pp |
| MHO | M/I Homes | 0.3% | 10.9x | -9.0% | 69.3% | 129.8% | +136pp |
| IBP | Installed Building Products | 2.5% | 20.5x | -19.3% | 68.1% | 100.0% | +106pp |
| DHI | D.R. Horton | -1.0% | 12.5x | -21.9% | 34.2% | 71.4% | +77pp |
| Industry | Names | 1Y med | 3Y med | 5Y med | Top 3 by 5Y |
|---|---|---|---|---|---|
| Education Services | 14 | -15.5% | 72.8% | 72.7% | CVSA 221% · LINC 213% · PRDO 207% |
| Homebuilding ← | 18 | -11.8% | 39.0% | 57.8% | GRBK 228% · PHM 161% · TOL 160% |
| Specialty Stores | 7 | -2.2% | 43.1% | 23.9% | FIVE 32% · DKS 30% · ASO 28% |
| Hotels, Resorts & Cruise Lines | 21 | 6.5% | 34.8% | 3.0% | RCL 216% · MAR 141% · HLT 132% |
| Automotive Retail | 18 | -17.3% | 3.2% | 0.9% | MUSA 222% · PAG 126% · ORLY 110% |
| Home Improvement Retail | 5 | -26.4% | -3.9% | -2.6% | HVT 15% · LOW -2% · HD -3% |
| Home Furnishings | 4 | -6.4% | 31.1% | -13.2% | SGI 44% · LZB 3% · MHK -29% |
| Footwear | 9 | 55.9% | 56.6% | -13.8% | WEYS 198% · DECK 30% · SHOO 25% |
| Distributors | 4 | -14.9% | -25.3% | -14.9% | ARMK 124% · GPC 19% · LKQ -49% |
| Restaurants | 36 | -12.6% | -13.1% | -16.9% | EAT 302% · CAKE 164% · BH-A 121% |
| Specialized Consumer Services | 10 | -18.8% | 10.5% | -19.3% | HRB 92% · FTDR 85% · SCI 35% |
| Leisure Products | 13 | -22.8% | -20.8% | -37.2% | GOLF 82% · HAS 26% · MAT -18% |
| Household Appliances | 18 | 4.2% | -0.1% | -39.3% | FLXS 236% · HBB 183% · KEQU 159% |
| Automotive Parts & Equipment | 38 | -14.9% | -12.8% | -42.2% | MOD 1361% · GTX 276% · CAAS 77% |
| Apparel Retail | 25 | -2.2% | 19.4% | -42.3% | ANF 247% · URBN 170% · ROST 123% |
| Computer & Electronics Retail | 3 | -2.7% | 50.5% | -42.6% | BBY 4% · GME -43% · UPBD -62% |
| Leisure Facilities | 11 | 3.9% | -8.8% | -44.6% | JAKK 163% · OSW 129% · ESCA 26% |
| Apparel, Accessories & Luxury Goods | 29 | -9.4% | 17.9% | -48.8% | TPR 249% · RL 235% · ELA 197% |
| Broadline Retail | 15 | 0.5% | 21.5% | -49.0% | DDS 343% · EBAY 66% · AMZN 56% |
| Casinos & Gaming | 20 | -21.0% | -28.1% | -49.6% | MCRI 93% · RRR 19% · BYD 9% |
| Consumer Electronics | 11 | -16.5% | -14.6% | -70.6% | AXIL 3426% · GRMN 98% · SONO -44% |
| Automobile Manufacturers | 8 | -78.5% | -49.5% | -76.8% | GM 50% · TSLA 42% · F 15% |
| Other Specialty Retail | 18 | -39.6% | -42.1% | -79.8% | TLF 96% · BBW 82% · WINA 61% |
Latest Trefis Analyses
Research & Analysis
Invest in Strategies
Wealth Management
Peer Comparisons
| Peers to compare with: |
Financials
| Median | |
|---|---|
| Name | |
| Mkt Price | 125.35 |
| Mkt Cap | 18.0 |
| Rev LTM | 13,583 |
| Op Inc LTM | 1,879 |
| FCF LTM | 1,068 |
| FCF 3Y Avg | 1,315 |
| CFO LTM | 1,129 |
| CFO 3Y Avg | 1,385 |
Growth & Margins
| Median | |
|---|---|
| Name | |
| Rev Chg LTM | -7.3% |
| Rev Chg 3Y Avg | -0.8% |
| Rev Chg Q | -10.1% |
| QoQ Delta Rev Chg LTM | -2.7% |
| Op Inc Chg LTM | -25.6% |
| Op Inc Chg 3Y Avg | -12.2% |
| Op Mgn LTM | 12.6% |
| Op Mgn 3Y Avg | 15.2% |
| QoQ Delta Op Mgn LTM | -0.8% |
| CFO/Rev LTM | 10.0% |
| CFO/Rev 3Y Avg | 8.5% |
| FCF/Rev LTM | 9.4% |
| FCF/Rev 3Y Avg | 7.9% |
Valuation
| Median | |
|---|---|
| Name | |
| Mkt Cap | 18.0 |
| P/S | 1.2 |
| P/Op Inc | 9.3 |
| P/EBIT | 9.3 |
| P/E | 12.0 |
| P/CFO | 12.4 |
| Total Yield | 9.8% |
| Dividend Yield | 1.1% |
| FCF Yield 3Y Avg | 5.9% |
| D/E | 0.2 |
| Net D/E | 0.1 |
Returns
| Median | |
|---|---|
| Name | |
| 1M Rtn | -4.7% |
| 3M Rtn | -13.1% |
| 6M Rtn | -1.8% |
| 12M Rtn | -18.6% |
| 3Y Rtn | 25.4% |
| 1M Excs Rtn | -5.6% |
| 3M Excs Rtn | -14.2% |
| 6M Excs Rtn | -19.2% |
| 12M Excs Rtn | -32.1% |
| 3Y Excs Rtn | -59.5% |
Comparison Analyses
Segment Financials
Revenue by Segment| $ Mil | 2025 | 2024 | 2023 | 2022 | 2021 |
|---|---|---|---|---|---|
| Homebuilding | 32,267 | 33,906 | 32,661 | 31,951 | 25,545 |
| Financial Services | 1,198 | 1,109 | 977 | 810 | 899 |
| Multifamily | 681 | 412 | 573 | 866 | 665 |
| Lennar Other | 41 | 14 | 22 | 44 | 21 |
| Total | 34,187 | 35,441 | 34,233 | 33,671 | 27,131 |
| $ Mil | 2024 | 2023 | 2022 | 2021 | 2020 |
|---|---|---|---|---|---|
| Homebuilding | 5,342 | 5,528 | 6,777 | 5,032 | 2,989 |
| Financial Services | 481 | ||||
| Lennar Other | -10 | ||||
| Multifamily | 23 | ||||
| Total | 5,342 | 5,528 | 6,777 | 5,032 | 3,482 |
| $ Mil | 2025 | 2024 | 2023 | 2022 | 2021 |
|---|---|---|---|---|---|
| Homebuilding | 29,253 | 35,594 | 33,628 | 32,684 | 27,468 |
| Financial Services | 3,377 | 3,517 | 3,567 | 3,254 | 2,964 |
| Multifamily | 902 | 1,307 | 1,382 | 1,257 | 1,312 |
| Lennar Other | 898 | 895 | 658 | 789 | 1,464 |
| Total | 34,430 | 41,313 | 39,234 | 37,984 | 33,208 |
Price Behavior
| Market Price | $79.81 | |
| Market Cap ($ Bil) | 19.5 | |
| First Trading Date | 11/05/1987 | |
| Distance from 52W High | -39.1% | |
| 50 Days | 200 Days | |
| DMA Price | $83.72 | $93.54 |
| DMA Trend | down | down |
| Distance from DMA | -4.7% | -14.7% |
| 3M | 1YR | |
| Volatility | 35.2% | 37.4% |
| Downside Capture | 204.30 | 131.83 |
| Upside Capture | 121.22 | 54.65 |
| Correlation (SPY) | 44.1% | 33.8% |
| 1M | 2M | 3M | 6M | 1Y | 3Y | |
|---|---|---|---|---|---|---|
| Beta | 1.92 | 1.81 | 1.41 | 1.28 | 0.98 | 0.83 |
| Up Beta | 1.01 | 1.62 | 0.33 | 1.11 | 1.21 | 0.84 |
| Down Beta | 4.18 | 2.85 | 1.77 | 1.38 | 0.90 | 0.52 |
| Up Capture | 163% | 169% | 144% | 104% | 47% | 56% |
| Bmk +ve Days | 6 | 16 | 27 | 66 | 132 | 424 |
| Stock +ve Days | 11 | 21 | 31 | 64 | 119 | 376 |
| Down Capture | 217% | 196% | 198% | 157% | 119% | 104% |
| Bmk -ve Days | 16 | 26 | 37 | 60 | 120 | 328 |
| Stock -ve Days | 11 | 21 | 33 | 62 | 133 | 374 |
[1] Upside and downside betas calculated using positive and negative benchmark daily returns respectively
Based On 1-Year Data
| Annualized Return | Annualized Volatility | Sharpe Ratio | Correlation with LEN | |
|---|---|---|---|---|
| LEN | -36.6% | 37.3% | -1.15 | - |
| Sector ETF (XLY) | -8.2% | 19.5% | -0.57 | 42.9% |
| Equity (SPY) | 16.2% | 13.0% | 0.88 | 33.5% |
| Gold (GLD) | 6.8% | 29.6% | 0.22 | 16.6% |
| Commodities (DBC) | 44.9% | 20.8% | 1.67 | -30.1% |
| Real Estate (VNQ) | 1.5% | 13.6% | -0.15 | 44.4% |
| Bitcoin (BTCUSD) | -28.9% | 44.3% | -0.64 | 2.2% |
Smart multi-asset allocation framework can stack odds in your favor. Learn How
Based On 5-Year Data
| Annualized Return | Annualized Volatility | Sharpe Ratio | Correlation with LEN | |
|---|---|---|---|---|
| LEN | -2.9% | 35.2% | -0.01 | - |
| Sector ETF (XLY) | 4.4% | 24.1% | 0.14 | 54.6% |
| Equity (SPY) | 13.1% | 17.2% | 0.58 | 50.7% |
| Gold (GLD) | 18.4% | 18.9% | 0.79 | 11.7% |
| Commodities (DBC) | 10.3% | 19.6% | 0.41 | -4.7% |
| Real Estate (VNQ) | 0.7% | 18.8% | -0.07 | 56.6% |
| Bitcoin (BTCUSD) | 14.6% | 52.2% | 0.45 | 21.5% |
Smart multi-asset allocation framework can stack odds in your favor. Learn How
Based On 10-Year Data
| Annualized Return | Annualized Volatility | Sharpe Ratio | Correlation with LEN | |
|---|---|---|---|---|
| LEN | 7.6% | 37.7% | 0.31 | - |
| Sector ETF (XLY) | 11.8% | 22.2% | 0.48 | 56.0% |
| Equity (SPY) | 15.3% | 17.9% | 0.72 | 53.0% |
| Gold (GLD) | 11.5% | 16.4% | 0.57 | 12.6% |
| Commodities (DBC) | 8.2% | 18.1% | 0.37 | 10.2% |
| Real Estate (VNQ) | 4.2% | 20.7% | 0.16 | 55.8% |
| Bitcoin (BTCUSD) | 64.1% | 66.2% | 1.04 | 13.8% |
Smart multi-asset allocation framework can stack odds in your favor. Learn How
Returns Analyses
Earnings Returns History
Updated 9/25/2026| Forward Returns | |||
|---|---|---|---|
| Earnings Date | 1D Returns | 5D Returns | 21D Returns |
| 9/16/2026 | 1.7% | 4.0% | |
| 6/11/2026 | -4.9% | -5.5% | -11.3% |
| 3/12/2026 | 2.6% | 1.3% | -3.0% |
| 12/16/2025 | -4.5% | -10.9% | 0.9% |
| 9/19/2025 | -4.2% | -1.0% | -0.7% |
| 6/17/2025 | -1.1% | 4.9% | 5.1% |
| 3/20/2025 | -4.0% | -1.7% | -13.6% |
| 12/18/2024 | -5.2% | -5.0% | -6.7% |
| ... | |||
| SUMMARY STATS | |||
| # Positive | 10 | 11 | 12 |
| # Negative | 15 | 14 | 12 |
| Median Positive | 3.1% | 4.9% | 5.3% |
| Median Negative | -4.1% | -4.0% | -4.9% |
| Max Positive | 13.8% | 11.4% | 23.1% |
| Max Negative | -7.6% | -10.9% | -13.6% |
| Forward Returns | |||
|---|---|---|---|
| Earnings Date | 1D Returns | 5D Returns | 21D Returns |
| 9/16/2026 | 1.7% | 4.0% | |
| 6/11/2026 | -4.9% | -5.5% | -11.3% |
| 3/12/2026 | 2.6% | 1.3% | -3.0% |
| 12/16/2025 | -4.5% | -10.9% | 0.9% |
| 9/19/2025 | -4.2% | -1.0% | -0.7% |
| 6/17/2025 | -1.1% | 4.9% | 5.1% |
| 3/20/2025 | -4.0% | -1.7% | -13.6% |
| 12/18/2024 | -5.2% | -5.0% | -6.7% |
| 9/19/2024 | -5.3% | -4.9% | -1.6% |
| 6/17/2024 | -5.0% | -4.7% | 9.0% |
| 3/13/2024 | -7.6% | -1.1% | -3.4% |
| 12/14/2023 | -3.6% | -4.5% | -3.4% |
| 9/14/2023 | -2.5% | -3.9% | -6.8% |
| 6/14/2023 | 4.4% | 5.7% | 14.0% |
| 3/14/2023 | -0.6% | 2.7% | 3.0% |
| 12/14/2022 | 3.8% | -0.3% | 8.8% |
| 9/21/2022 | 2.0% | 2.1% | -5.5% |
| 6/21/2022 | 1.6% | 11.4% | 23.1% |
| 3/16/2022 | 0.9% | -4.1% | -13.3% |
| 12/15/2021 | -4.1% | -0.7% | -4.4% |
| 9/20/2021 | -0.5% | 1.2% | 1.9% |
| 6/16/2021 | 3.6% | 6.2% | 5.3% |
| 3/16/2021 | 13.8% | 7.4% | 16.0% |
| 12/16/2020 | 7.6% | 5.8% | 5.3% |
| 9/14/2020 | -3.9% | -2.8% | 5.1% |
| SUMMARY STATS | |||
| # Positive | 10 | 11 | 12 |
| # Negative | 15 | 14 | 12 |
| Median Positive | 3.1% | 4.9% | 5.3% |
| Median Negative | -4.1% | -4.0% | -4.9% |
| Max Positive | 13.8% | 11.4% | 23.1% |
| Max Negative | -7.6% | -10.9% | -13.6% |
SEC Filings
Expand for More| Report Date | Filing Date | Filing |
|---|---|---|
| 02/28/2026 | 04/09/2026 | 10-Q |
| 11/30/2025 | 01/28/2026 | 10-K |
| 08/31/2025 | 10/03/2025 | 10-Q |
| 05/31/2025 | 07/01/2025 | 10-Q |
| 02/28/2025 | 04/04/2025 | 10-Q |
| 11/30/2024 | 01/23/2025 | 10-K |
| 08/31/2024 | 10/02/2024 | 10-Q |
| 05/31/2024 | 06/28/2024 | 10-Q |
| 02/29/2024 | 03/29/2024 | 10-Q |
| 11/30/2023 | 01/26/2024 | 10-K |
| 08/31/2023 | 09/29/2023 | 10-Q |
| 05/31/2023 | 06/30/2023 | 10-Q |
| 02/28/2023 | 04/04/2023 | 10-Q |
| 11/30/2022 | 01/26/2023 | 10-K |
| 08/31/2022 | 10/04/2022 | 10-Q |
| 05/31/2022 | 07/01/2022 | 10-Q |
| Report Date | Filing Date | Filing |
|---|---|---|
| 02/28/2026 | 04/09/2026 | 10-Q |
| 11/30/2025 | 01/28/2026 | 10-K |
| 08/31/2025 | 10/03/2025 | 10-Q |
| 05/31/2025 | 07/01/2025 | 10-Q |
| 02/28/2025 | 04/04/2025 | 10-Q |
| 11/30/2024 | 01/23/2025 | 10-K |
| 08/31/2024 | 10/02/2024 | 10-Q |
| 05/31/2024 | 06/28/2024 | 10-Q |
| 02/29/2024 | 03/29/2024 | 10-Q |
| 11/30/2023 | 01/26/2024 | 10-K |
| 08/31/2023 | 09/29/2023 | 10-Q |
| 05/31/2023 | 06/30/2023 | 10-Q |
| 02/28/2023 | 04/04/2023 | 10-Q |
| 11/30/2022 | 01/26/2023 | 10-K |
| 08/31/2022 | 10/04/2022 | 10-Q |
| 05/31/2022 | 07/01/2022 | 10-Q |
| 02/28/2022 | 04/01/2022 | 10-Q |
| 11/30/2021 | 01/28/2022 | 10-K |
| 08/31/2021 | 10/01/2021 | 10-Q |
| 05/31/2021 | 07/02/2021 | 10-Q |
| 02/28/2021 | 04/01/2021 | 10-Q |
| 11/30/2020 | 01/22/2021 | 10-K |
| 08/31/2020 | 10/01/2020 | 10-Q |
| 05/31/2020 | 07/06/2020 | 10-Q |
| 02/29/2020 | 04/07/2020 | 10-Q |
| 11/30/2019 | 01/27/2020 | 10-K |
| 08/31/2019 | 10/08/2019 | 10-Q |
| 05/31/2019 | 07/03/2019 | 10-Q |
Recent Forward Guidance
Updated 9/17/2026Latest: Q3 2026 Earnings Reported 9/16/2026
| Forward Guidance | Guidance Change | |||||||
|---|---|---|---|---|---|---|---|---|
| Metric | Source | Low | Mid | High | % Chg | % Delta | Change | Prior |
| Q4 2026 New Orders | Reported | 19500 | 20000 | 20500 | -7.0% | Lower New | Guidance: 21500 for Q3 2026 | |
| Q4 2026 Deliveries | Reported | 22000 | 22500 | 23000 | 7.1% | Higher New | Guidance: 21000 for Q3 2026 | |
| Q4 2026 Financial Services Operating Earnings | Reported | 90.00 Mil | 92.50 Mil | 95.00 Mil | -5.1% | Lower New | Guidance: 97.50 Mil for Q3 2026 | |
| Q4 2026 Average Sales Price | Reported | 0.37 Mil | 0.38 Mil | 0.38 Mil | -0.7% | Lower New | Guidance: 0.38 Mil for Q3 2026 | |
| Q4 2026 Gross Margin % on Home Sales | Reported | 15.5% | 15.75% | 16.0% | -0.2% | Lower New | Guidance: 16.0% for Q3 2026 | |
| Q4 2026 SG&A % of Home Sales | Reported | 8.7% | 8.85% | 9.0% | -0.0% | Lower New | Guidance: 8.9% for Q3 2026 | |
| 2026 Target Deliveries | Reported | 80000 | 80500 | 81000 | -2.4% | Lowered | Guidance: 82500 for 2026 | |
Prior: Q2 2026 Earnings Reported 6/11/2026
| Forward Guidance | Guidance Change | |||||||
|---|---|---|---|---|---|---|---|---|
| Metric | Source | Low | Mid | High | % Chg | % Delta | Change | Prior |
| Q3 2026 New Orders | Reported | 21000 | 21500 | 22000 | 0 | Affirmed | Guidance: 21500 for Q2 2026 | |
| Q3 2026 Deliveries | Reported | 20500 | 21000 | 21500 | 2.4% | Higher New | Guidance: 20500 for Q2 2026 | |
| Q3 2026 Financial Services Operating Earnings | Reported | 95.00 Mil | 97.50 Mil | 100.00 Mil | -7.1% | Lower New | Guidance: 105.00 Mil for Q2 2026 | |
| Q3 2026 Average Sales Price | Reported | 0.38 Mil | 0.38 Mil | 0.38 Mil | 1.3% | Higher New | Guidance: 0.37 Mil for Q2 2026 | |
| Q3 2026 Gross Margin % on Home Sales | Reported | 16.0% | 0.2% | Higher New | Guidance: 15.75% for Q2 2026 | |||
| Q3 2026 SG&A % of Home Sales | Reported | 8.8% | 8.9% | 9.0% | -0.1% | Lower New | Guidance: 9.0% for Q2 2026 | |
| 2026 Deliveries | Reported | 82000 | 82500 | 83000 | Lowered | |||
Q1 2026 Earnings Reported 3/12/2026
| Forward Guidance | Guidance Change | |||||||
|---|---|---|---|---|---|---|---|---|
| Metric | Source | Low | Mid | High | % Chg | % Delta | Change | Prior |
| Q2 2026 New Orders | Reported | 21000 | 21500 | 22000 | 16.2% | Higher New | Guidance: 18500 for Q1 2026 | |
| Q2 2026 Deliveries | Reported | 20000 | 20500 | 21000 | 17.1% | Higher New | Guidance: 17500 for Q1 2026 | |
| Q2 2026 Financial Services Operating Earnings | Reported | 100.00 Mil | 105.00 Mil | 110.00 Mil | -2.3% | Lower New | Guidance: 107.50 Mil for Q1 2026 | |
| Q2 2026 Average Sales Price | Reported | 0.37 Mil | 0.37 Mil | 0.38 Mil | 0.7% | Higher New | Guidance: 0.37 Mil for Q1 2026 | |
| Q2 2026 Gross Margin % on Home Sales | Reported | 15.5% | 15.75% | 16.0% | 0.2% | Higher New | Guidance: 15.5% for Q1 2026 | |
| Q2 2026 SG&A % of Home Sales | Reported | 8.9% | 9.0% | 9.1% | -0.5% | Lower New | Guidance: 9.5% for Q1 2026 | |
Q4 2025 Earnings Reported 12/16/2025
| Forward Guidance | Guidance Change | |||||||
|---|---|---|---|---|---|---|---|---|
| Metric | Source | Low | Mid | High | % Chg | % Delta | Change | Prior |
| Q1 2026 Deliveries | Reported | 17000 | 17500 | 18000 | -22.2% | Lower New | Actual: 22500 for Q4 2025 | |
| Q1 2026 New Orders | Reported | 18000 | 18500 | 19000 | -9.8% | Lower New | Actual: 20500 for Q4 2025 | |
| Q1 2026 Financial Services Operating Earnings | Reported | 105.00 Mil | 107.50 Mil | 110.00 Mil | -18.9% | Lower New | Actual: 132.50 Mil for Q4 2025 | |
| Q1 2026 Average Sales Price | Reported | 0.36 Mil | 0.37 Mil | 0.38 Mil | -3.9% | Lower New | Actual: 0.39 Mil for Q4 2025 | |
| Q1 2026 S,G&A % of Home Sales | Reported | 9.5% | 1.6% | Higher New | Actual: 7.9% for Q4 2025 | |||
| Q1 2026 Gross Margin % on Home Sales | Reported | 15.0% | 15.5% | 16.0% | -2.0% | Lower New | Actual: 17.5% for Q4 2025 | |
| 2026 Deliveries | Reported | 85000 | ||||||
Insider Activity
Updated 9/30/2026| # | Owner | Title | Holding | Action | Filing Date | Price | Shares | Transacted Value | Value of Held Shares | Form |
|---|---|---|---|---|---|---|---|---|---|---|
| 1 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 81.59 | 638,813 | 52,120,753 | 2,124,149,633 | Form | |
| 2 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 79.98 | 4,008 | 320,560 | 44,228,940 | Form | |
| 3 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 81.95 | 12,289 | 1,007,084 | 2,081,171,305 | Form | |
| 4 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 80.00 | 100 | 8,000 | 43,919,360 | Form | |
| 5 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 81.96 | 5,200 | 426,192 | 2,080,418,055 | Form |
| # | Owner | Title | Holding | Action | Filing Date | Price | Shares | Transacted Value | Value of Held Shares | Form |
|---|---|---|---|---|---|---|---|---|---|---|
| 1 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 81.59 | 638,813 | 52,120,753 | 2,124,149,633 | Form | |
| 2 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 79.98 | 4,008 | 320,560 | 44,228,940 | Form | |
| 3 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 81.95 | 12,289 | 1,007,084 | 2,081,171,305 | Form | |
| 4 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 80.00 | 100 | 8,000 | 43,919,360 | Form | |
| 5 | Berkshire, Hathaway Inc | See footnote | Buy | 9302026 | 81.96 | 5,200 | 426,192 | 2,080,418,055 | Form | |
| 6 | Berkshire, Hathaway Inc | See footnote | Buy | 9252026 | 81.15 | 485,102 | 39,364,958 | 2,059,379,628 | Form | |
| 7 | Berkshire, Hathaway Inc | See footnote | Buy | 9252026 | 79.53 | 7,022 | 558,460 | 43,653,381 | Form | |
| 8 | Berkshire, Hathaway Inc | See footnote | Buy | 9252026 | 80.90 | 640,930 | 51,853,995 | 2,013,953,388 | Form | |
| 9 | Berkshire, Hathaway Inc | See footnote | Buy | 9252026 | 79.54 | 12,390 | 985,472 | 43,099,069 | Form | |
| 10 | Berkshire, Hathaway Inc | See footnote | Buy | 9252026 | 81.65 | 532,993 | 43,518,878 | 1,980,184,128 | Form | |
| 11 | Berkshire, Hathaway Inc | See footnote | Buy | 9252026 | 79.99 | 1,263 | 101,027 | 42,353,105 | Form | |
| 12 | Berkshire, Hathaway Inc | See footnote | Buy | 9212026 | 77.79 | 644,084 | 50,100,626 | 1,845,011,223 | Form | |
| 13 | Berkshire, Hathaway Inc | See footnote | Buy | 9212026 | 76.44 | 23,034 | 1,760,661 | 40,375,588 | Form | |
| 14 | Berkshire, Hathaway Inc | See footnote | Buy | 9212026 | 76.52 | 1,346,675 | 103,043,629 | 1,765,633,365 | Form | |
| 15 | Berkshire, Hathaway Inc | See footnote | Buy | 9212026 | 74.91 | 34,722 | 2,600,918 | 37,841,699 | Form | |
| 16 | Berkshire, Hathaway Inc | See footnote | Buy | 9212026 | 79.02 | 677,749 | 53,552,463 | 1,716,869,610 | Form | |
| 17 | Berkshire, Hathaway Inc | See footnote | Buy | 9212026 | 77.43 | 17,265 | 1,336,854 | 36,428,485 | Form |
Investor Activity (13F)
Updated Oct 5, 2026Active managers (13F portfolio over $250M, at least 3 holdings) with a position over $5M that is either over 10% of their portfolio or held in a concentrated book of 50 or fewer total positions. Index/ETF, sovereign, bank, community-bank and charitable/donor-advised filers are excluded.
| Active Manager | Value | % of Portfolio | Total Positions | QoQ | Filing |
|---|---|---|---|---|---|
| Greenhaven Associates Inc | $953.9 Mil | 15.7% | 27 | ADD +5.1% | 13F |
| Sophron Capital Management L.P. | $17.7 Mil | 5.2% | 41 | ADD +476.4% | 13F |
| Brave Warrior Advisors, LLC | $209.3 Mil | 5.2% | 36 | Hold | 13F |
| GoodHaven Capital Management, LLC | $13.7 Mil | 4.8% | 24 | ADD +8.2% | 13F |
| Smead Capital Management, Inc. | $137.7 Mil | 3.0% | 32 | TRIM -13.0% | 13F |
| Prescott General Partners LLC | $28.0 Mil | 2.1% | 10 | ADD +1515.0% | 13F |
| Horiko Capital Management LLC | $7.6 Mil | 1.8% | 20 | Hold | 13F |
| Magnolia Group, LLC | $9.1 Mil | 1.7% | 12 | ADD +53.1% | 13F |
| First Washington CORP | $5.5 Mil | 1.6% | 50 | Hold | 13F |
| Deltroit Asset Management (UK) LLP | $7.7 Mil | 1.3% | 39 | ADD +329.5% | 13F |
| Active Manager | Value | % of Portfolio | Total Positions | QoQ | Filing |
|---|---|---|---|---|---|
| Prescott General Partners LLC | $28.0 Mil | 2.1% | 10 | ADD +1515.0% | 13F |
| Sophron Capital Management L.P. | $17.7 Mil | 5.2% | 41 | ADD +476.4% | 13F |
| Deltroit Asset Management (UK) LLP | $7.7 Mil | 1.3% | 39 | ADD +329.5% | 13F |
| Magnolia Group, LLC | $9.1 Mil | 1.7% | 12 | ADD +53.1% | 13F |
| GoodHaven Capital Management, LLC | $13.7 Mil | 4.8% | 24 | ADD +8.2% | 13F |
| Greenhaven Associates Inc | $953.9 Mil | 15.7% | 27 | ADD +5.1% | 13F |
| Active Manager | Value | % of Portfolio | Total Positions | QoQ | Filing |
|---|---|---|---|---|---|
| Greenhaven Associates Inc | $953.9 Mil | 15.7% | 27 | ADD +5.1% | 13F |
| Brave Warrior Advisors, LLC | $209.3 Mil | 5.2% | 36 | Hold | 13F |
| Smead Capital Management, Inc. | $137.7 Mil | 3.0% | 32 | TRIM -13.0% | 13F |
| Prescott General Partners LLC | $28.0 Mil | 2.1% | 10 | ADD +1515.0% | 13F |
| Sophron Capital Management L.P. | $17.7 Mil | 5.2% | 41 | ADD +476.4% | 13F |
| GoodHaven Capital Management, LLC | $13.7 Mil | 4.8% | 24 | ADD +8.2% | 13F |
| Magnolia Group, LLC | $9.1 Mil | 1.7% | 12 | ADD +53.1% | 13F |
| Deltroit Asset Management (UK) LLP | $7.7 Mil | 1.3% | 39 | ADD +329.5% | 13F |
| Horiko Capital Management LLC | $7.6 Mil | 1.8% | 20 | Hold | 13F |
| First Washington CORP | $5.5 Mil | 1.6% | 50 | Hold | 13F |
LEN Trade Sentinel
Neutral / Watch
CONVICTION RATIONALE
Lennar guides for a significant Q3 gross margin recovery to approximately 16%, a potential inflection from a trailing 8.8%. However, this is set against negative free cash flow of -$90.2 million and rising net debt. The investment case hinges on this guided margin improvement materializing and beginning to repair cash generation.
STOCK ARCHETYPE
Cyclical Project-Based(Number of Homes Delivered) x (Average Selling Price) Gross Margin % recovery, driven by a reduction in sales incentives and continued construction cost control.
INVESTMENT THESIS
Evidence points to a potential bottoming in profitability, with management guiding for a sharp near-term gross margin recovery despite lowered full-year volume expectations.
- Management guides for Q3 2026 gross margins of approximately 16%.
- Sales incentives on deliveries declined to 12.9% in Q2 2026.
- Management views the incentive decline as a potential 'leading indicator of margin recovery'.
- The company's five-year peak operating margin was 21%, showing significant recovery potential.
PRIMARY RISK
The company is funding shareholder returns with debt, as trailing-twelve-month free cash flow was negative $90.2 million while net debt increased to $2.9 billion from $1.1 billion a year earlier. This strategy is unsustainable if operating cash flow does not improve significantly, creating balance sheet risk.
- Trailing-twelve-month free cash flow was negative $90.2 million.
- Net debt increased to $2.9 billion from $1.1 billion in the prior year.
- Operating cash flow was $72.4 million against net income of $1.8 billion.
- Full-year 2026 delivery guidance was lowered to a range of 82,000 to 83,000 homes.
| KPI | Status | Rationale |
|---|---|---|
| New Orders | 21,749 homes in the second quarter of fiscal 2026 - Decelerating | The year-over-year decline in New Orders in the latest quarter marks a deceleration from the first quarter's performance. Management attributed the weakness to a challenging macro environment, including stubbornly elevated mortgage rates and wavering consumer confidence. |
| Sales Incentives | 12.9% of home sales revenue in the second quarter of fiscal 2026 - Turning around | Management highlighted the sequential and year-over-year decline in incentives as an encouraging signal and a potential "leading indicator of margin recovery." Despite this improvement, the overall level remains elevated, reflecting the affordability-constrained market. |
| Home Deliveries | 20,519 (Q2 2026 (three months ended May 31, 2026)) | Represents the number of homes closed and revenue recognized in the period, reflecting current operational output. |
| Construction Cycle Time | a hundred and 21 days (Q2 2026) | Measures the time from start to completion of a home. A lower number indicates greater operational efficiency, faster inventory turns, and improved capital efficiency. |
Margin Inflection vs. Cash Burn
BULL VIEW
Bulls focus on leading indicators: sales incentives fell to 12.9% and Q3 gross margin is guided to ~16%. This signals a sharp profitability recovery is underway, making the deeply negative trailing-twelve-month margin of 8.8% irrelevant.
CORE TENSION
Can guided Q3 margin recovery to ~16% reverse the narrative from negative cash flow and severe peer underperformance on trailing margins of 8.8%?
PREVAILING SENTIMENT
The latest evidence favors the bears, as the negative cash flow is a reported fact. The bull case rests entirely on achieving future guidance, which has not yet been confirmed.
BEAR VIEW
Bears see the trailing-twelve-month negative free cash flow of -$90.2 million and rising net debt as proof the model is broken. The company is borrowing to fund buybacks, a sign of financial stress that margin hopes cannot obscure.
| Timeline | Event & Metric To Watch |
|---|---|
10/20/2026 | Peer Margin Outperformance Watch: Peer earnings reports confirming continued wide margin gaps, pressuring Lennar's stock and strategy narrative. |
10/22/2026 | PulteGroup Earnings Report Watch: Peer PulteGroup is scheduled to report earnings. |
10/26/2026 | Meritage Homes Earnings Report Watch: Peer Meritage Homes is scheduled to report earnings. |
12/14/2026 | Failure to Meet Guidance Watch: A miss on Q3 delivery or margin guidance in the December earnings report, signaling worsening demand or pricing pressure. |
12/14/2026 | Lennar Earnings Report Watch: Lennar is scheduled to report its next earnings. |
No set date | Worsening Housing Affordability Watch: Further increases in mortgage rates or signs of weakening consumer confidence, which could force higher incentives and pressure future guidance. |
| Date | Event | Stock Impact |
|---|---|---|
2026-07-13 | Mortgage Rates Trend Higher Details: Press reports in mid-July noted that mortgage rates were heading higher, creating bad news for homebuilders as homes become less affordable. | -0.7% $84.27 -> $83.71 |
2026-06-17 | Q2 Results Show Declines Details: Press reports on June 17 highlighted Lennar's Q2 results, where adjusted EPS fell 31.1% year-over-year and total revenues declined 5.2% year-over-year. | -0.1% $89.25 -> $89.20 |
2026-06-12 | Negative Q2 Earnings Reaction Details: The stock reacted negatively to the June 12 earnings call, with a two-day stock reaction of -5.0% versus 2.0% for the S&P 500. | -5.5% $94.39 -> $89.22 |
2026-06-11 | Full-Year Guidance Lowered Details: At its June 11 earnings report, the company lowered its guidance for full-year 2026 deliveries, setting a new midpoint of 82,500 homes. | +0.5% $89.32 -> $89.76 |
2026-03-15 | Management Outlines Q1 Strategy Details: On its March 15 earnings call, management stated it was prioritizing consistent volume, cost reductions, and an asset-light model to navigate a 'stubbornly challenging' housing market. | +3.7% $91.51 -> $94.88 |
2026-03-13 | Positive Q1 Earnings Reaction Details: The stock reacted positively to the March 13 earnings call, with a two-day stock reaction of 4.0% versus 0.0% for the S&P 500. | +3.7% $91.51 -> $94.88 |
Position Sizing
4% - 6%
NORMAL POSITION
Sizing is volatility-based: LEN trades at roughly 38% annualized options-implied volatility versus about 13% for the S&P 500 (2.8x the market), around the 38th percentile of its own trailing year. A 4% - 6% position keeps a single-name swing of that size within a diversified portfolio's risk budget.
Diversification Alternatives
DHI - D.R. Horton
Scale with ProfitabilityD.R. Horton matches Lennar's scale with a trailing-twelve-month revenue of $33.3 billion, but operates with a vastly superior gross margin of 22.6% versus Lennar's 8.8%.
PHM - a business partner
Higher-End & Margin Leadera business partner focuses more on move-up and active adult buyers with a build-to-order model, achieving a sector-leading gross margin of 25.2%.
Lennar is an asset-light home manufacturer using its scale to drive down costs and maintain production volume through a cyclical downturn, positioning itself for significant margin expansion when housing affordability improves.
Lennar is navigating a difficult housing market characterized by high interest rates and affordability challenges. Its core strategy is to maintain a consistent volume of home sales by using incentives to "price to market," accepting near-term margin compression. This volume-first approach is designed to drive down construction costs and improve operational efficiencies like cycle time, creating a more resilient, lower-cost manufacturing platform. The thesis is that when macroeconomic headwinds subside, Lennar's leveraged cost structure and market position will allow for a rapid recovery in profitability as incentives are reduced.
Sustained sequential declines in sales incentives, sequential improvement in gross margins, and stable or growing new order volumes despite a challenging macro environment.
A sharp increase in cancellation rates, rising construction costs that cannot be offset, or a severe drop in new orders forcing even deeper price cuts to maintain volume.
Short-term fluctuations in stock price or monthly housing data that do not alter the underlying trend of affordability and consumer confidence.
Repricing Catalyst
A sustained decline in mortgage rates or meaningful government action on housing affordability, which would unlock pent-up demand and allow the company to reduce incentives, leading to a sharp recovery in gross margins.
Homebuilding
$31.3B TTM (94% of Total)What It Is
Constructs and sells single-family attached and detached homes to a diverse customer base including first-time, move-up, active adult, and luxury homebuyers across various U.S. markets.
Who Pays & How
Individual homebuyers pay for the homes upon closing. They are drawn to Lennar's value-oriented pricing, its "Everything's Included" marketing program which simplifies the buying process by including desirable features as standard, and innovative designs like the "Next Gen" home for multi-generational families.
Competition
Financial Services
$1.1B TTM (3% of Total)What It Is
Provides mortgage financing, title insurance, and closing services primarily to buyers of Lennar homes. It also originates and sells commercial mortgage loans.
Who Pays & How
Homebuyers pay for these services as part of the home purchasing and financing process. The segment captures a high percentage of Lennar's homebuyers (84% of those who obtained mortgages in FY2025) by offering an integrated and simplified financing experience alongside the home purchase.
Competition
Multifamily
$700M TTM (2% of Total)What It Is
Develops, constructs, and manages multifamily rental communities, often through joint ventures and longer-duration funds.
Who Pays & How
Tenants pay rent for apartments. Investment partners provide capital for development projects in exchange for returns.
Competition
Lennar Other
$57M TTM (0% of Total)What It Is
This segment primarily consists of strategic investments in technology companies related to the homebuilding and financial services industries, as well as legacy fund investments.
Who Pays & How
This segment does not have a traditional customer base; its results are driven by the performance and valuation of its investments.
Competition
Lennar — Investor Video Playlist



Industry Resources
| Consumer Discretionary Resources |
| Retail Dive |
| Business of Fashion (BoF) |
| WWD (Women's Wear Daily) |
| National Retail Federation (NRF) |
| McKinsey & Company - Consumer |
| Mintel Consumer Trends |
| Homebuilding Resources |
| Builder Online |
| Professional Builder |
| HousingWire |
External Quote Links
| Y Finance | Barrons |
| TradingView | Morningstar |
| SeekingAlpha | ValueLine |
| Motley Fool | Robinhood |
| CNBC | Etrade |
| MarketWatch | Unusual Whales |
| YCharts | Perplexity Finance |
| FinViz |
Prefer one of these to Trefis? Tell us why.