
Omnicell Vulnerable To Downside Risk If Acquisition Talks Fail
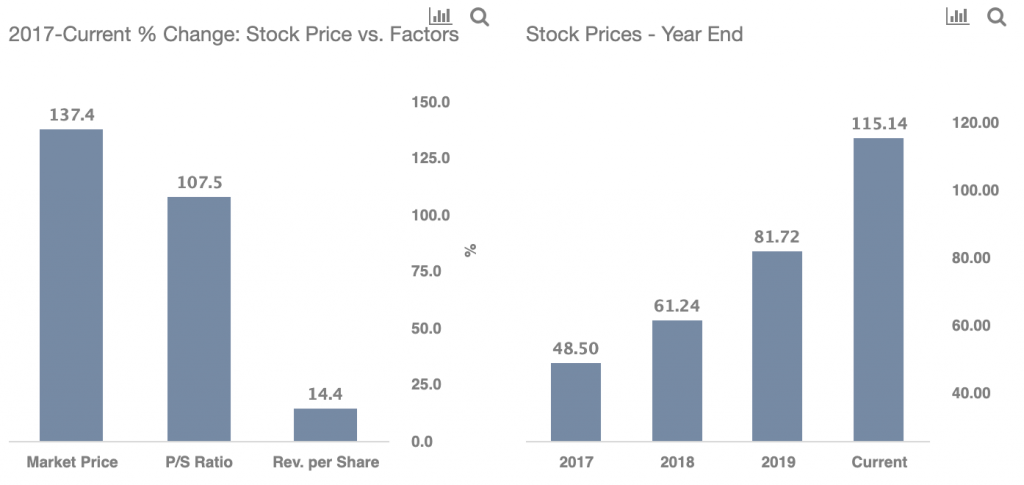
After a solid 2x rise since March lows of this year, at the current price of around $115 per share, Omnicell stock (NASDAQ: OMCL), a medication management services provider, has reached its near term potential, in our view. OMCL stock has rallied from $55 to $115, outperforming the S&P which moved 65% over the same period, with the resumption of economic activities as lockdowns are gradually lifted. The outperformance can be attributed to better than estimated Q3 results and the reported talks of its acquisition at over $120 per share by Baxter International. OMCL stock is also up 137% from levels of $48 seen in early 2018, over two years ago.
Some of the 137% rise of the last 2 years is justified by the roughly 26% growth seen in Omnicell’s revenues from 2017 to 2019. The company saw a 10% growth in total shares outstanding due to share issuance, resulting in a 14% growth in revenue per share (RPS) to $21.64 in 2019, compared to $18.92 in 2017. With the growth in RPS, the company’s P/S (price-to-sales) ratio also expanded. We believe the stock is likely to see downside after the recent uptick and the potential weakness from a recession-driven by the Covid outbreak. Our dashboard, ‘What Factors Drove 137% Change in Omnicell Stock between 2017 and now?, has the underlying numbers.
Omnicell’s P/S multiple changed from 2.6x in 2017 to 3.8x in 2019. Now that the company’s P/S has expanded to 5.3x, there is a potential downside risk when the current P/S is compared to levels seen in the past years, P/S of around 2.6x at the end of 2017 and 3.1x in 2018. While the stock looks expensive based on valuation, its movement will also depend on the news around its acquisition.
So what’s the likely trigger and timing for downside?
The global spread of Coronavirus has impacted the bookings of Omnicell due to fewer hospital visits. That said, the company is now seeing a rebound in demand. The company’s management, in its latest quarterly earnings conference call, reinstated its pre-pandemic booking guidance of $865 million to $900 million for the full year. More importantly, the stock price growth of late is being driven by a possible acquisition by Baxter, which is reported to have valued Omnicell at $5 billion, compared to the $3.2 billion valuation the company was trading at in early October 2020.
Omnicell’s total revenue in the first three quarters of 2020 was down 1% y-o-y to $643 million, while the adjusted earnings of $1.63 per share reflect a 20% decline over the $2.04 figure reported in the prior year period, primarily led by higher operating costs, owing to the pandemic. Looking forward, with economies opening up gradually and the upcoming availability of vaccines, the hospital visits are expected to rise, boding well for Omnicell. That said, much of these factors appear to be priced in the current stock value of $115, despite the expected recovery in demand post Covid. In reality, 2020 full year revenues are estimated to see a decline of 1.4% to $884 million, while earnings are expected to be down 15% to $2.38.
Looking at the broader economy, the actual recovery and its timing hinge on the containment of the coronavirus spread. Our dashboard Trends In U.S. Covid-19 Cases provides an overview of how the pandemic has been spreading in the U.S. and contrasts with trends in Brazil and Russia. Following the Fed stimulus — which set a floor on fear — the market has been willing to “look through” the current weak period and take a longer-term view. With investors focusing their attention on 2021 results, the valuations become important in finding value. Though market sentiment can be fickle, and evidence of an uptick in new cases could spook investors once again. At levels of around $115, OMCL stock is trading at 5.5x its 2020 expected RPS of $20.75, and 4.8x its 2021 expected RPS of $24.17. This compares with P/S of 2.6x seen in 2017, 3.1x seen in 2018, and 3.8x seen as recently as late 2019, making the stock appear vulnerable to downside risk, especially if the talks around its acquisition fail.
See all Trefis Price Estimates and Download Trefis Data here
What’s behind Trefis? See How It’s Powering New Collaboration and What-Ifs For CFOs and Finance Teams | Product, R&D, and Marketing Teams