
Earnings Review: Why Were Urban Outfitters’ Results Impressive?
- Urban Outfitters’ shares jumped almost 15% as its results came in ahead of the market expectations
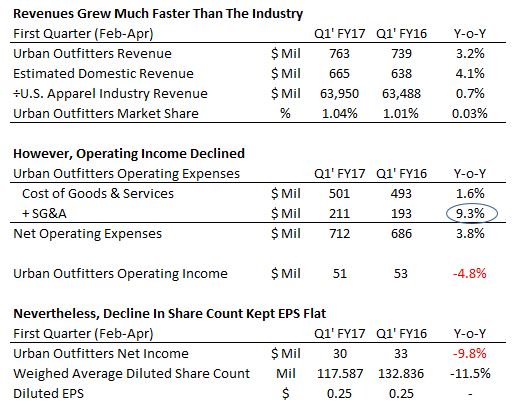
- Strong growth at Free People, the acquisition of Vetri and a surge in wholesale revenues helped the retailer post a modest revenue growth of 3.2%
- Wholesale revenues were driven by expansion into 200 new specialty and department stores
- Free People revenues were driven by the presence of 11 new retail outlets

- While revenues grew moderately, operating income fell 5% due to increase SG&A expenses, which may be attributed to higher online-related expenses
- However, a fall in share count, thanks to buybacks, kept EPS stable at $0.25
- For the full year, we expect revenues, EBITDA and EPS to grow in low-single digits, backed by continued expansion, growth in Vetri revenues, and fewer promotional activities owing to better merchandise

Have more questions about Urban Outfitters? See the links below:
- What Is Urban Outfitters’ Revenue & Net Income Breakdown In Terms of Different Operating Segments?
- How Has Urban Outfitters’ Revenue Composition Changed In The Last Five Years?
- What Is Urban Outfitters’ Fundamental Value Based On Expected 2016 Results?
Notes:
1) The purpose of these analyses is to help readers focus on a few important things. We hope such lean communication sparks thinking, and encourages readers to comment and ask questions on the comment section, or email content@trefis.com
2) Figures mentioned are approximate values to help our readers remember the key concepts more intuitively. For precise figures, please refer to our complete analysis for Urban Outfitters
Interactive Institutional Research (Powered by Trefis):
Global Large Cap | U.S. Mid & Small Cap | European Large & Mid Cap |More Trefis Research