
Here’s What Makes Logitech Stock A Good Bet
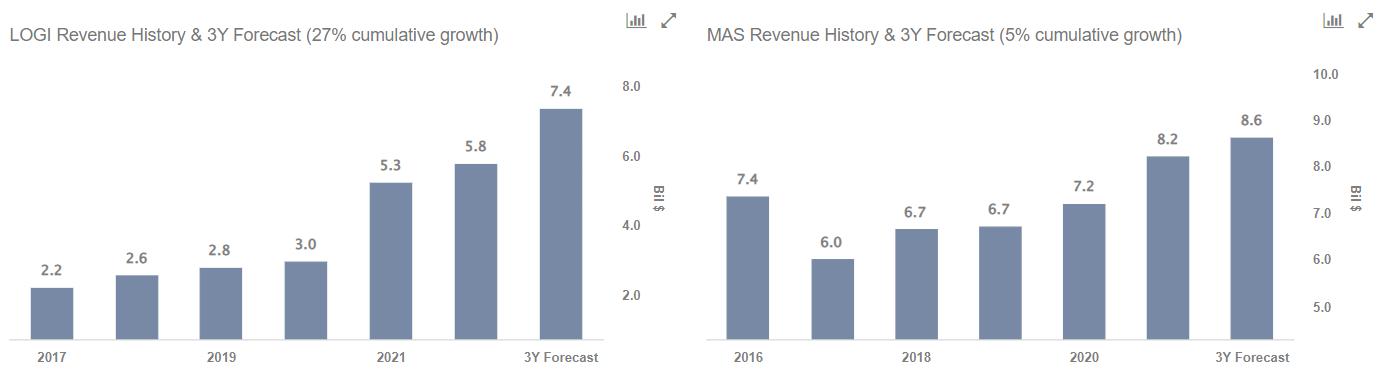
We think that Logitech International (NASDAQ:LOGI) currently is a better bet compared to Masco Corp (NYSE:MAS). Logitech stock trades at almost 2.5x trailing revenues, a little more than that of Masco, whose P/S multiple stands at 1.9x. Does this gap in the companies’ valuations make sense? We believe it does and we only expect this gap to widen. While both companies have performed well since the pandemic, Logitech has seen much stronger and faster revenue growth over the past few years compared to Masco. Logitech, a computer peripherals manufacturer, has seen its sales rise from $2.2 billion in FY ’17 to $5.8 billion on an LTM basis, a jump of more than 2.5x (Logitech’s fiscal year ends in March). On a comparable basis, Masco, a home improvement products manufacturer, saw its sales rise from $7.4 billion in FY ’16 to around $8.2 billion on an LTM basis, a growth of only 1.1x. For details about Masco’s revenues and comparison to peers, see Masco (MAS) Revenue Comparison.
Having said that, we dive deeper into the comparison, which makes Logitech a better bet than Masco, especially at these valuations. Let’s step back to look at the fuller picture of the relative valuation of the two companies by looking at detailed historical revenue growth as well as operating income growth and financial position, combined with expected returns. Our dashboard Logitech vs Masco: Similar Market Cap, But Logitech Is A Better Bet has more details on this. Parts of the analysis are summarized below.
1. Logitech Has Shown Much Faster Sales Growth
Logitech’s sales have risen from $2.2 billion in FY ’17 to $5.3 billion in FY ’21, and currently stand at around $5.8 billion on an LTM basis, a jump of around 2.5x over the past five years. In comparison, Masco’s sales dropped sharply from $7.4 billion in FY ’16 to around $6 billion in FY ’17, before steadily rising back up to $7.2 billion in FY ’20. Masco’s sales have since jumped further to $8.2 billion on an LTM basis.
Additionally, Logitech’s sales grew 25% QoQ, much more than Masco’s 1.1%. Further, in terms of revenue growth for the last three fiscal years, Logitech saw a growth of 30.6% compounded, much more than Masco’s 6.2%.
Finally, Logitech’s pre-Covid sales growth stands at 10.6% annually, more than Masco’s -2.8%, and growth during Covid, too, stands at 6.7% for Logitech, only slightly lower than Masco’s 7.2%.
2. EBIT margins And Financial Position: Mixed Bag
Logitech’s LTM EBIT margin change vs the last three fiscal years stands at -5.8%, much lower than Masco’s 2.6%. While for Logitech, current LTM margins stand at 7.7%, much lower than Masco’s 21.7%, Logitech has also seen much slower EBIT margin growth lately.
Additionally, Logitech’s debt as a % of equity stands at 0% currently, against Masco’s 19.5%. Further, Logitech is ahead in terms of cash as a % of assets, too, with 32.8%, compared to Masco’s 15.3%.
For additional details about Logitech’s historical returns and comparison to peers, see Logitech (LOGI) Stock Return.
3. Finally, Logitech Is Ahead In Terms Of Expected Returns
Using P/S as a base, due to high fluctuations in P/E and P/EBIT, we believe Logitech is currently the better choice. Logitech’s LTM revenues of $5.8 billion are expected to rise at a CAGR of around 8.3% as per our estimates, taking revenue numbers three years out to as high as $7.4 billion. Assuming Logitech’s P/S ratio to remain roughly at the same level as now, this means that the market cap would rise to around $18 billion, an upside of nearly 40% over three years.
In comparison, given historical trends, we expect Masco’s sales to rise much slower at a CAGR of 1.6%, taking revenue in three years to $8.6 billion. However, considering the P/S for Masco, too, to remain around current levels, we estimate the market cap to remain roughly unchanged over this period.
The Net of It All
While Masco’s sales are at a higher level than Logitech’s, the latter has witnessed much faster revenue growth over the years and has also posted a better performance during the recent period. Though Masco’s margins currently stand higher, we expect Logitech’s strong sales growth consistency to translate into a better margin performance in the near future and expect the gap between the two companies’ valuations to widen even further. As such, we believe that Logitech stock is currently a better bet compared to Masco stock.
What if you’re looking for a more balanced portfolio instead? Here’s a high-quality portfolio that’s beaten the market consistently since the end of 2016.
| Returns | Feb 2022 MTD [1] |
2022 YTD [1] |
2017-22 Total [2] |
| LOGI Return | -5% | -4% | 220% |
| MAS Return | -3% | -12% | 94% |
| S&P 500 Return | -1% | -6% | 100% |
| Trefis MS Portfolio Return | -1% | -10% | 254% |
[1] Month-to-date and year-to-date as of 2/7/2022
[2] Cumulative total returns since the end of 2016
Invest with Trefis Market-Beating Portfolios