
Weak FY’20 Numbers To Drag Down Littelfuse Stock?
Littelfuse stock (NASDAQ: LFUS) is up around 45% since the beginning of 2020, and at the current price around $279 per share, we believe that Littelfuse stock has significant potential downside.
Why is that? Our belief stems from the fact that LFUS stock is up more than 2.5x from its low in March 2020, while the S&P has moved over 70% in comparison. Further, with demand struggling to rise to pre-Covid levels and weak full-year 2020 results, we believe LFUS stock could head lower. Our dashboard What Factors Drove 62% Change In Littelfuse Stock Between 2018 And Now? provides the key numbers behind our thinking, and we explain more below.
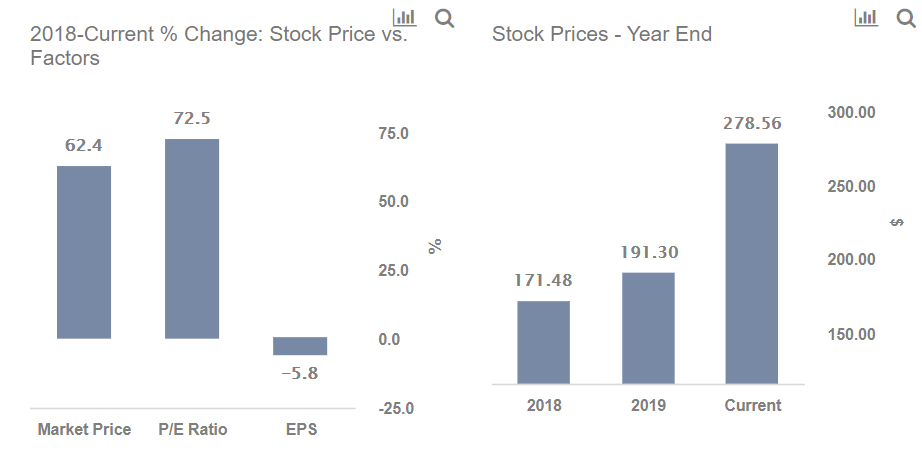
Littelfuse. a multinational electronic manufacturing company, primarily producing circuit protection products and switches and sensors, saw its stock price rise since 2018 despite a 4% drop in revenue from $1.5 billion in FY 2019 to $1.45 billion in FY 2020 (Littelfuse’s fiscal year ends in December). This combined with a 3% drop in the net margins meant that net income fell around 7%. Further, a roughly unchanged outstanding share count, led to earnings-per-share (EPS) dropping around 6%, from $5.66 to $5.33.
Also, LFUS saw its P/E (price-to-earnings) ratio jump from 30x in 2018 to 36x in 2019, and has since jumped to 52x, riding the rally in technology stocks. Given that industrial demand for electronics is still not back up to pre-Covid levels, we believe there is a possible downside risk for the P/E multiple.
So what’s the likely trigger and timing to this downside?
The global spread of coronavirus has led to a drop in demand for electronic hardware devices across all markets, which means lower demand for Littelfuse’s circuit protection and automatic switching products. This is evident from Littelfuse’s full-year 2020 results, where revenue came in at $1.45 billion, down from $1.5 billion in FY 2019. As operating expenses didn’t fall at the same rate, operating income took a bigger hit, dropping to $162 million, from $193 million in FY 2019. However, EPS came in only around 6% lower in comparison, largely helped by a foreign exchange gain of $20 million over the previous year.
Going forward, we expect revenues to stay weak in the near to medium term, and if the company is not able to control operating expenses, we believe the stock will see its P/E multiple decline from the current level of 52x to around 44x, which combined with a reduction in revenues and margins could result in the stock price shrinking to as low as $230, a downside of more than 15% from the current price near $279.
While Littelfuse stock may seem overvalued, 2020 has created many pricing discontinuities which can offer attractive trading opportunities. For example, you’ll be surprised how the stock valuation for Intel vs Cisco shows a disconnect with their relative operational growth. You can find many such discontinuous pairs here.
See all Trefis Price Estimates and Download Trefis Data here
What’s behind Trefis? See How It’s Powering New Collaboration and What-Ifs For CFOs and Finance Teams | Product, R&D, and Marketing Teams