
Does A Billion Dollar IPO For iQiyi Make Sense For Baidu?
According to recent reports, Chinese internet giant Baidu (NASDAQ:BIDU) is planning a $1 billion IPO for its online video streaming business iQiyi, valuing the business at around $5 billion. [1] Earlier this year, a consortium of investors led by Baidu CEO Robin Li wanted to buy out the iQiyi business for $2.3 billion, but later dropped the bid after investors claimed that the price was too low. [2] Various market research firms and hedge funds estimate iQiyi’s valuation at anywhere between $2.5 billion and $5.5 billion. [3] According to our estimates, the online video division makes up around 5% of our $178 price estimate for Baidu’s stock. Our price estimate is roughly 8-10% higher than the current market price, valuing the company at around $62 billion and the iQiyi business at around $3.1 billion.
[trefis_slideshow ticker=”BIDU” rhs=”3″]
See our complete analysis for Baidu
Baidu started its online video business back in 2012 in an attempt to capture the shifting customer demand from television to online video streaming. Baidu’s online video business includes its iQiyi video platform, which has an extensive video content library that includes licensed movies, television series, cartoons, variety shows and other programs. In addition to sourcing licensed content, iQiyi also produces a wide array of original content and provides online community services to facilitate user communication and interaction – similar to what Netflix (NASDAQ:NFLX) does in the U.S. and internationally. We forecast the company’s online video services revenues to increase at around 60% annually in 2016 to $1.3 billion – which would be about 11% of Baidu’s net revenues – making it the fastest growing revenue stream for Baidu.
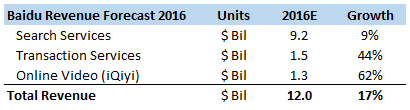
Although it is the fastest-growing revenue stream within the company, Baidu has operated its streaming video business at a loss over the past few years. The trend is likely to continue over the next few years until the segment matures. The operating costs for Baidu’s online video segment consist primarily of content acquisition costs, bandwidth costs, and other SG&A and marketing expenses. Content costs for iQiyi increased almost tenfold from $140 million in 2013 to to $1.3 billion in 2015. Similarly, both marketing expenses and bandwidth costs increased by over 80% in 2015. In the long run, however, we expect the business to generate positive margins for two primary reasons. Firstly, most of iQiyi’s bandwidth costs are fixed in nature, which means that these costs may not recur with revenue gains. Secondly, high content acquisition costs are unlikely to increase at the rate of revenue growth, owing to economies of scale. We currently forecast Baidu’s online video segment to report an operating profit starting in 2018.

According to an estimate by iResearch, the online video market in China has grown at a CAGR of over 70% since 2013 to become a RMB 14 billion ($1.8 billion) market by the end of 2015. [4] One of the key factors driving the online video market in China include internet penetration, which has increased from 35% of the population in 2010 to over 50% last year, [5] as well as an increasing mix of high-definition content on the internet. Another primary driver of current and expected growth is the mobile video business, which is being driven by increasing smartphone penetration in China. Factoring in these reasons, iResearch estimates that the online video market in China will grow at 55% this year and at a CAGR of just under 35% from 2016 through 2018 to become a RMB 110 billion market by 2018. In this market space, iQiyi primarily competes with Alibaba’s (NYSE:BABA) Youku Tudou, and Tencent’s video business, with all three roughly valued at $5-7 billion each. [1]

Baidu’s online video revenues grew at over 30% from 2013 through 2015, with its share in the market increasing from under 10% in 2013 to 13.3% in 2015. We forecast Baidu’s share in the market to go up to 15% by the end of 2018. Correspondingly, the company’s video revenues could continue to grow at around 25% annually over the next few years.
[trefis_forecast ticker=”BIDU” driver=”2080″]
Baidu has not only made large expenditures to acquire premium copyrighted movies and television shows, it has also produced original content exclusive to its platforms and affiliated third party platforms. Earlier this year,Baidu announced that it will invest roughly $1.4 billion to purchase and produce content in the coming year. ((Baidu Plans $1B IPO for Video-Streaming Site, Fox Business, December 2016)) Given the massive amount of investment required to compete with its rivals, it might make sense for the company to spin off the video business in the short term. According to our estimates, the iQiyi business is worth $3.1 billion to Baidu. If the company can raise $1 billion for iQiyi at a valuation of almost $5 billion, it could be a favorable decision for the company. You can modify the interactive charts in the article above to gauge how a change in the online video market and Baidu’s market share can have on our price estimate for Baidu.
[trefis_forecast ticker=”BIDU” driver=”2078″]
View Interactive Institutional Research (Powered by Trefis):
Global Large Cap | U.S. Mid & Small Cap | European Large & Mid Cap
More Trefis Research
- Baidu Plans $1 Billion IPO for Video-Streaming Site iQiyi.com, Wall Street Journal, December 2016 [↩] [↩]
- Group Led by Baidu CEO Abandons Bid to Buy Out Video Unit, Wall Street Journal, July 2016 [↩]
- Baidu Plans $1B IPO for Video-Streaming Site, Fox Business, December 2016 [↩]
- The revenue of China’s Online Video Companies Totaled 39.7 Bn Yuan in 2015, iResearch China, April 2016 [↩]
- China Internet Users, Internet Live Stats, July 2016 [↩]