
Is Lockheed Martin Stock Riskier Than It Looks?
Today’s big story: Could Nvidia Stock Fall 50%? Follow The Cash
The risk at Lockheed Martin (LMT) is less about winning orders than about timing. The stock returned 31.7% over the year to November 16, 2026, compared with an 11.4% return for the S&P 500. The company’s order backlog also ended fiscal Q3 2026 at a record $292 billion. Yet in October, management said its 2026 forecast for the company’s largest business was slightly lower than in July. So why did management lower that forecast?
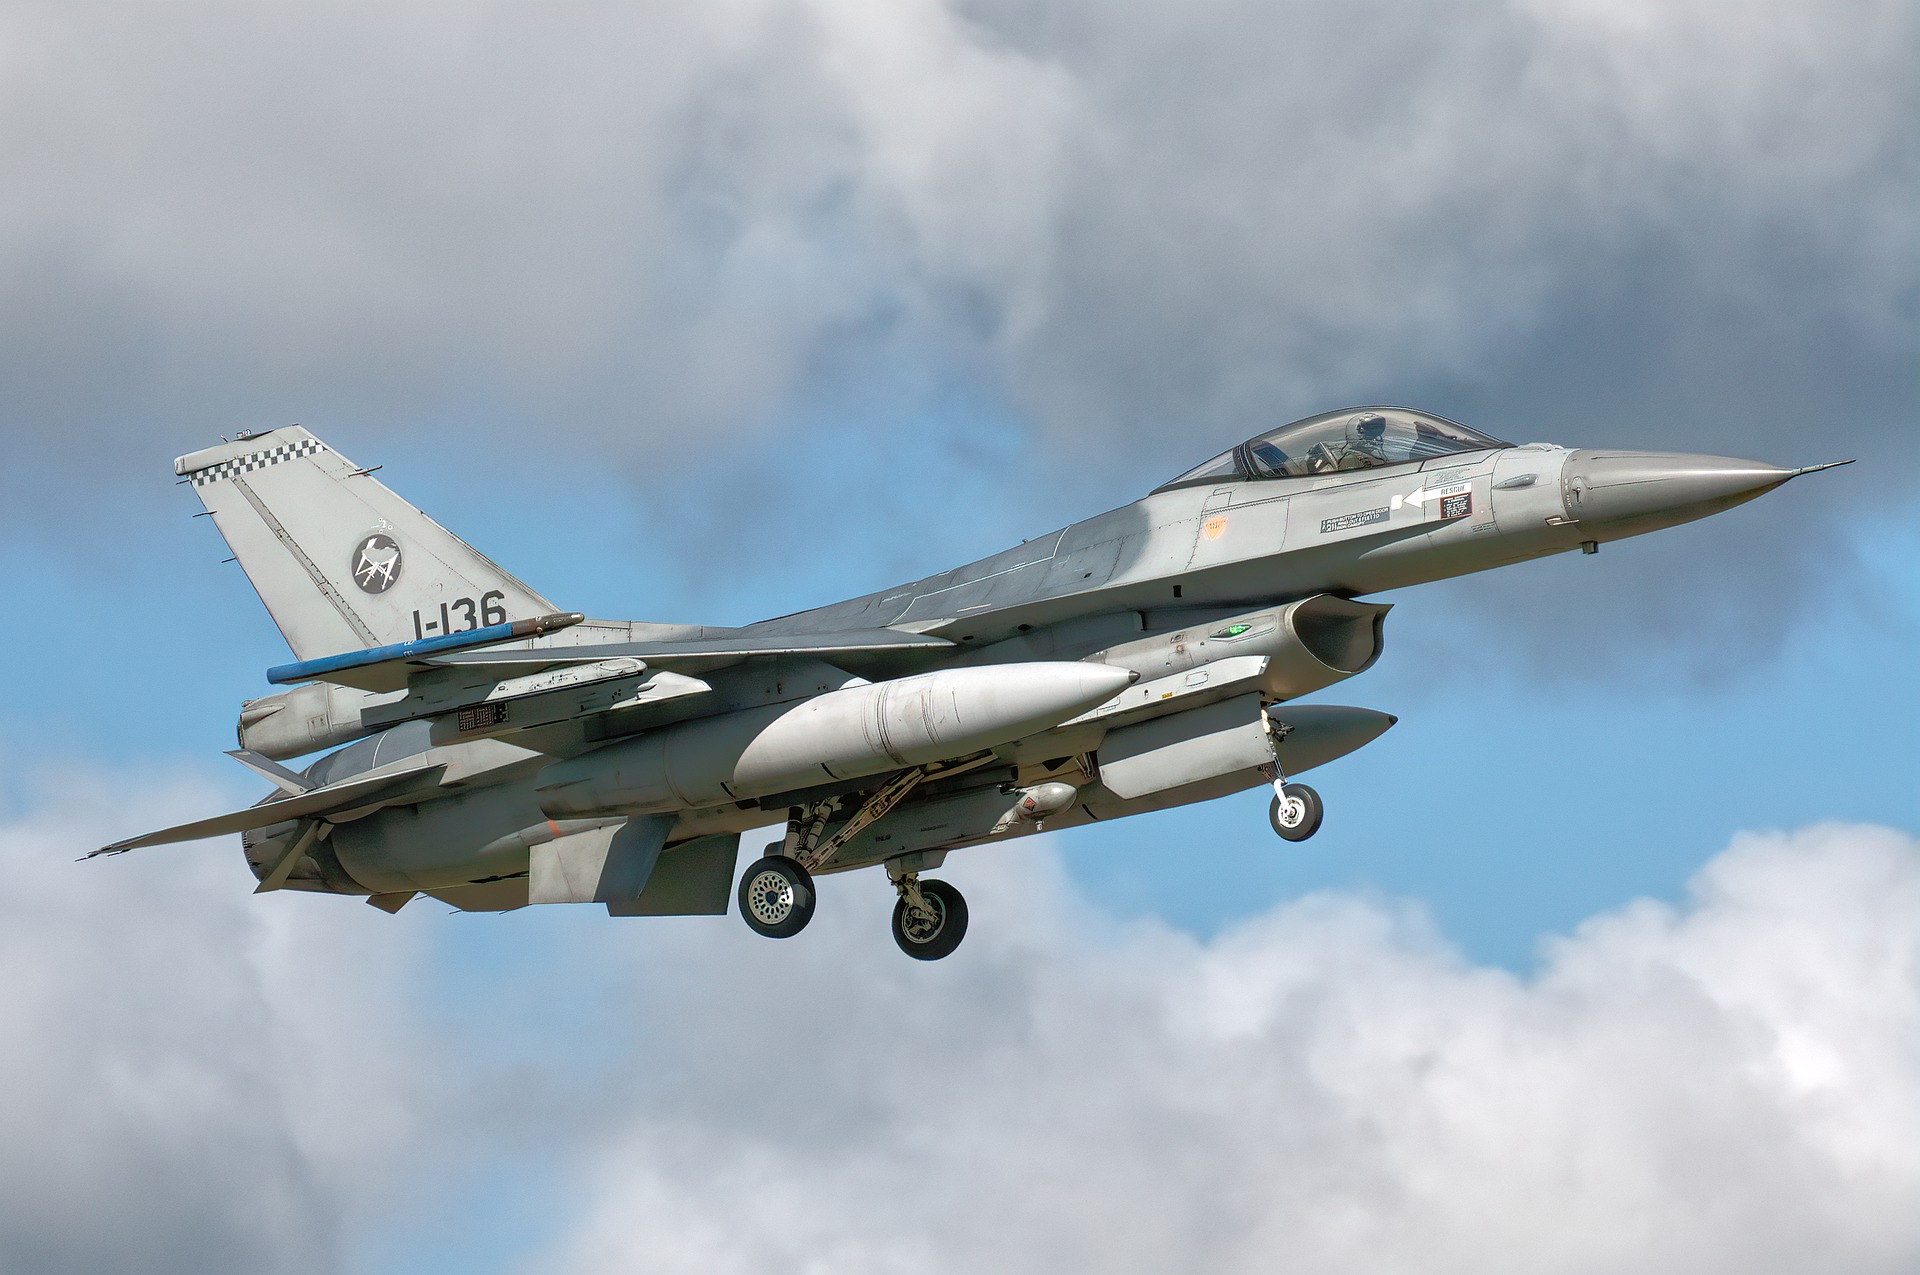
Lockheed Martin Is Waiting On The Government To Sign
Management tied the lower forecast for Aeronautics, the business building the F-35 fighter, to a shift in when it expects the next lots of F-35 jets to be awarded. It also said the 2026 forecast excludes the contract for one of those lots, Lot 20, even as advance procurement funds keep work on it well underway.
This caution extends beyond a single program. On the October 22 call, management said the U.S. government opened fiscal 2027 under a continuing resolution, and extra funding through reconciliation is still taking shape. Management argued that demand for its weapons has bipartisan support and is not tied to any single bill or election. The risk that management described therefore points to slower contract signings by the U.S. government rather than fewer orders.
How Big Is Lockheed Martin’s Aeronautics Business?
Aeronautics operates as Lockheed Martin’s largest business. The division generated $30.6 billion of sales in fiscal 2025, more than any of its other three segments. Segment sales grew 5.7% that year, following a 4.4% increase in fiscal 2024.
For 2026, management expects Aeronautics sales growth of 3% to 7%. That is slower than the roughly 8% growth management expects for the whole company, the midpoint of its $80 billion to $82 billion sales forecast.
That slower growth matters for the share price. Lockheed Martin stock closed on November 16, 2026, 12.4% below its highest close of the past year, reached on March 2. At that close, the stock traded at 20.7 times its last twelve months of earnings, against 21.9 for the S&P 500. Its price of 1.7 times sales is not far below 1.9, the highest it reached at any quarter end since fiscal Q4 2016.
Is Lockheed Martin’s F-35 Timing Already In The Price?
Only partly. A stock trading close to the S&P 500 on earnings, and near the top of its own history on sales, appears to assume the next F-35 contracts will arrive without a long wait. Lockheed Martin therefore carries more risk than its record backlog implies, although the risk centers on when those sales arrive rather than whether they do.
Management said that with the recent F-35 agreement, Lockheed Martin is on a path to 850 U.S. aircraft over a 10-year span, and that signing Lot 20 in 2026 would be upside to effectively all its 2026 numbers. It also said the company can start production under its contracts even when government funding takes more time. F-35 timing presents a real risk, but a slow one.
Aeronautics sales remain the measure to watch at Lockheed Martin’s next report, expected in January 2027, when management also plans to issue its 2027 guidance.
Even a company holding a record order book can see a year’s sales slip on a date set by the U.S. government. That reality offers a good reason to know how much of your money sits in one stock and how you would step out of it.
Too Much Riding On One Stock?
If Lockheed Martin is a big part of your wealth, so are its risk and its tax bill. What’s your exit plan? Our partner advisory firm offers a free 30-minute strategy review covering a floor under losses and a lower-tax way out.
Spot an error or want more like this? Tell us in 10 seconds.