
One Reason United Airlines Stock Looks Better Than Its Price
For questions about this article or underlying research, email help@trefis.com.
United Airlines (UAL) is fitting its jets with Starlink, and that may be what its bulls are betting on. You probably see United as one more airline squeezed by costs, with operating margin over the past twelve months thinning to 6.4% from 8.8% a year earlier. Yet management says Starlink is pulling travelers from other airlines. That is the tension. So how far has United gone with Starlink?
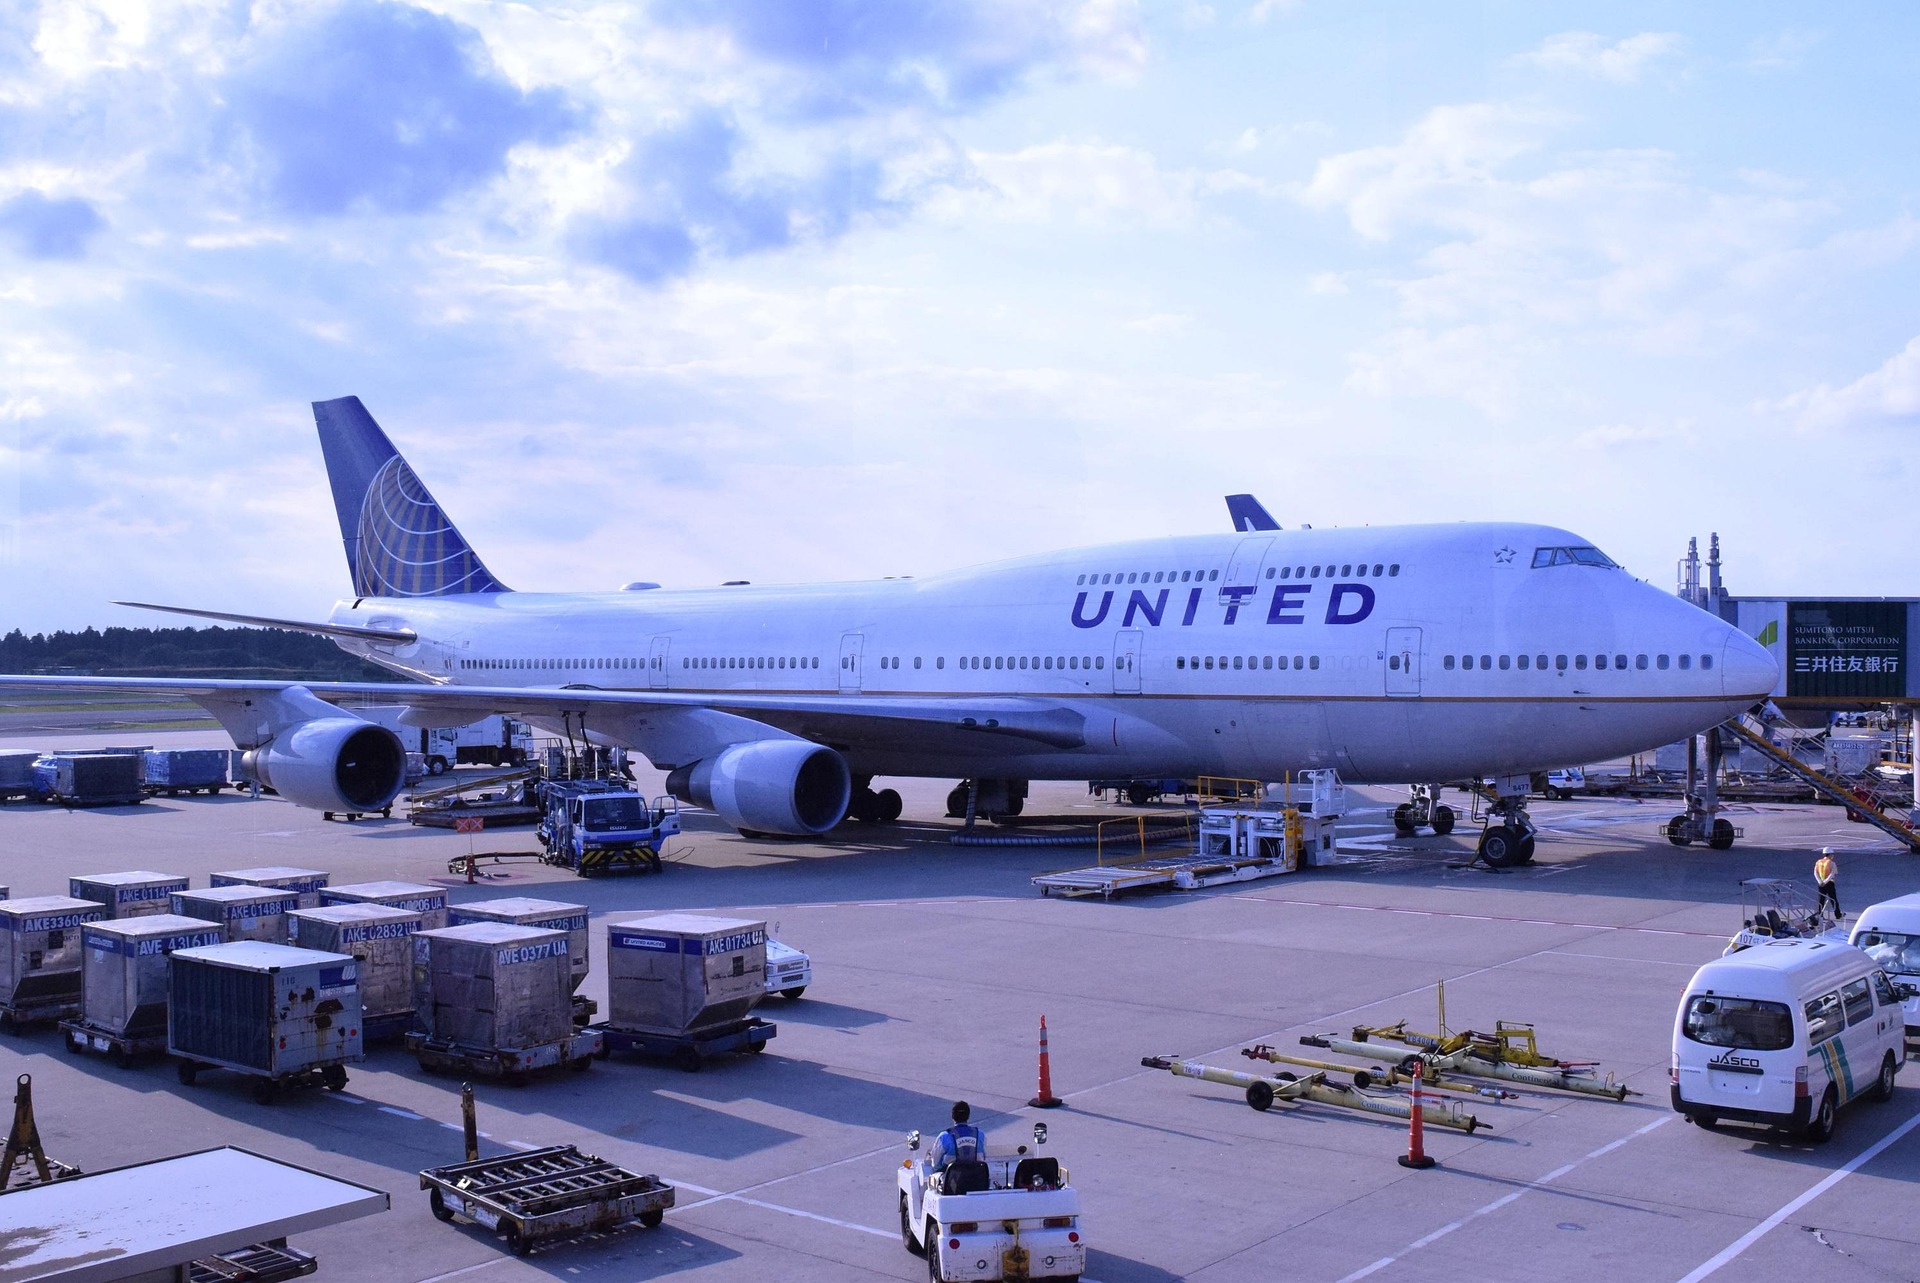
United Has Starlink On About Half Of Departures
About half of United’s departures now fly on aircraft with Starlink. On its October 21, 2026 call, management said United offers more Starlink flights than the entire US airline industry combined. It expects to reach 61% of departures by the end of 2026 and to finish installing Starlink on all its mainline and express jets by the end of 2027.
Management says Starlink is already winning customers. It called the evidence mostly anecdotal, but said travelers who had been loyal to other airlines for years switched to United solely because of Starlink. Management also calls Starlink critical for its business customers, whose revenue rose 22% in the third quarter of 2026. Revenue from business contracts rose faster still, by 26%. Business yields, a measure of fares, rose 15% in the quarter, management said. It sees Starlink as a key driver of revenue and share growth in 2027.
Is Starlink Enough To Lift United’s Margins?
Not on its own, by management’s account. It expects a meaningful lift from Starlink in 2027 to revenue per seat mile, what United earns for each seat it flies a mile, but said that is probably not enough by itself to reach its goal of double-digit pretax margins. For that, management said it probably also needs lower fuel, slower industry capacity growth or airlines that keep flying emptier planes in return for higher fares.
Fuel is the worry. On October 20, 2026, United forecast fourth-quarter profit below estimates as fuel costs bit. Management said fuel prices drove a $1.8 billion rise in third-quarter expense from a year earlier, and United recaptured 72% of that increase. Management said it passes higher fuel costs on through higher ticket prices. It expects fourth-quarter earnings per share of $0.50 to $1.50, assuming fuel at about $4.80 a gallon.
At the November 12, 2026 close, United’s shares were worth $36.1 billion. That price is 10.1 times the company’s earnings over the past twelve months, against 21.9 times for the S&P 500. United’s own multiple was below 10.1 at 30 of its last 40 quarter ends, though that count includes quarters when it lost money and the multiple was negative, falling as low as -14.1 in September 2022.
What Could Go Wrong For United Airlines Holders?
Fuel and seats could both work against United. Management expects fuel to remain elevated for all of 2027, and said industry capacity appears set to grow faster. In past market shocks the stock has fallen hard, dropping by 47% in the 2025 US Tariff Shock from February to June 2025, against 19% for the SPDR S&P 500 ETF.
United also carries heavy debt, totaling $34.3 billion at the end of September 2026. That equals 94.9% of its market value, against 19.5% for the S&P 500, and management said United paid down about $1 billion of debt in the third quarter. It also raised $900 million of new debt, and total debt was $31.3 billion a year earlier.
United is betting that Starlink brings travelers, business travelers above all, to its flights. Revenue per seat mile is the measure to watch when United reports fourth-quarter results, expected in January 2027.
Want A Second Look At What You Own?
United Airlines is one decision in a portfolio. Whether you work with an advisor or manage your money yourself, a second look at the whole portfolio costs nothing. Our partner advisory firm offers a free written review of your holdings, fees and income plan, with no need to switch.
Spot an error or want more like this? Tell us in 10 seconds.